

Chase is refreshing the Chase Freedom Flex®, which is largely positive for new and current cardholders.
On Sept. 22, 2026, the following changes to the card go into effect:
- No foreign transaction fee. Previously, the Chase Freedom Flex® charged a 3% fee on foreign transactions. With the change, the card becomes an excellent travel companion, especially for overseas dining purchases.
- No cell phone insurance. The card used to offer secondary cell phone coverage of up to $800 per claim and $1,000 per year for damage or theft. There was a $50 deductible per claim and a limit of two claims per 12 months. To qualify for coverage, cardholders had to pay their cell phone bills with the card.
- A new limited-time welcome bonus. New cardholders can qualify for a welcome offer worth $250 after spending $500 in the first 3 months from account opening, a boost of $50 from the previous offer. Note that this bonus is a limited-time promotion.
- Early look at bonus categories. Once a year, Chase will preview the upcoming quarter’s bonus categories rather than waiting until two weeks before the start of the quarter. For example, Chase already announced the bonus categories for the first quarter of 2027: grocery stores and select streaming services. This advance notice may help consumers be more strategic about future spending to maximize their reward earnings.
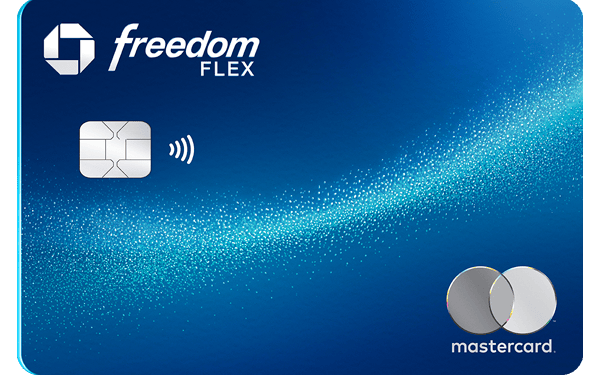
- New card design.
🤓Nerdy Tip
Foreign transaction fees appear to have also been eliminated on the "legacy" Chase Freedom® card, the precursor to the Chase Freedom Flex®. Chase stopped accepting applications for the original Freedom card in 2020, when it launched the Flex. But existing cardholders were able to keep using it, and it remains an option for product changes. NerdWallet staffers with the legacy Freedom report that the card benefits listed in the Chase app now include "no foreign transaction fees." At first glance, the loss of cell phone insurance degrades the Chase Freedom Flex®. But this credit card benefit has become less valuable in recent years. To qualify for cell phone insurance with your credit card, you have to pay your wireless bill with that card. But many wireless companies now offer discounts for paying with a bank account or their own co-branded credit card. Cell phone protection is also widely available through the major wireless carriers, too (though not for free, of course).
All other benefits of the Chase Freedom Flex® are staying the same. That includes the 5% cash back in rotating quarterly bonus categories on up to $1,500 in combined quarterly spending. (Activation of bonus categories is required.)
Chase Freedom® and Chase Freedom Flex® bonus rewards categories for 2026 | ||
|---|---|---|
Q1 (Jan. 1-March 31) |
| |
Q2 (April 1-June 30) |
| |
Q3 (July 1-Sept. 30) |
| |
Q4 (Oct. 1-Dec. 31) |
| |
The card also earns 5% back on travel booked through Chase, 3% back on dining and at drugstores, and 1% on all other non-bonus-category purchases. Other benefits include trip protection, rental car insurance, and a 0% intro APR on Purchases and Balance Transfers for 15 months, and then the ongoing APR of 18.24%-27.74% Variable APR.
That’s a solid combination of benefits for a card that doesn’t charge annual or foreign transaction fees.