


The rising-rate environment is here, and my high-yield savings account hasn’t met the moment.
Writing about bank accounts for a living gives me a good sense of high-yield opportunities, and in this case, I knew my current savings rate could be closer to 4% than 3% annual percentage yield. So I opened a new account.
Getting the EverBank savings account
Getting the Performance Savings account at EverBank was fast and easy. The bank's website and mobile app prioritize security and function over an engaging design, and customer support by phone was helpful.
But for a high-yield savings account, finding my APY wasn’t easy and I faced some uncertainty over whether my APY will eventually stop matching what’s advertised on the website. Here’s a breakdown of my account-opening experience.
EverBank’s savings account is stellar at a glance
Competitive APY: When I opened the account in late August, my rate was 3.90%. It has since gone up to 4.20%, matching what is currently listed on EverBank's website as the "new account APY." That rate increase was a recent change likely due to the Federal Reserve raising its rate for the first time in years. EverBank holds a top rate among high-yield savings accounts that we list on NerdWallet.
No upfront or ongoing costs: There’s no monthly fee and no minimum balance to open or maintain the account.
Online-focused experience with highly rated mobile apps: EverBank is mostly an online bank with a nationwide reach, though it has a few branches in certain cities in California, Florida and New York. The iOS and Android apps have mostly standard features in a clean, basic interface. The savings account specifically is only available to open online or by phone.
The application process was fast
From clicking “Open now” on EverBank’s website to account approval, the process took me 11 minutes. There were three parts: account selection, customer identification and the opening deposit portion.
Multiple account ownership types for different customers: EverBank offers single, joint and custodial accounts (such as for parents and kids). Not every online bank has all three.
Quick identification: After I chose a single account, verifying my identity with my Social Security number took less than a minute. No photo ID or document uploads were needed. The required personal details were standard, such as name, U.S. address and employment status. The only field that gave me pause was the occupation dropdown list, which was limited enough that I chose “other.”
Convenient opening deposit with Plaid: Like many banks, EverBank uses the third-party data connector firm Plaid. After handing over my external bank login to Plaid, my online transfer request went through in minutes without needing a routing or account number. There were other funding methods that would’ve taken longer or cost more: wire transfers, check by mail and direct deposit.
Fast transfers in and out: EverBank said processing would take one to two business days, which is a standard time frame. My transfer took one business day: I did the transfer at 4 p.m. on a Friday and money settled in my account by the following Monday. Weeks later, I tested a transfer out on a Wednesday, and the money was delivered to my external bank that Thursday.
But I’ll need to keep a close eye on my APY
High-yield savings account rates are subject to change at any time, but it’s fair to assume that a bank generally raises (or lowers) the same rate on new and existing savings accounts.
EverBank’s website, however, reads: “Annual Percentage Yield (APY) is for new accounts only and may not apply to existing accounts.” There is no mention of any other APY for savings accounts.
NerdWallet reached out to an EverBank spokesperson about how long the APY lasts for new accounts, what happens once an account is no longer considered new, and if there’s a different APY for existing accounts. The spokesperson reiterated the website language without answering our questions.
Contrast that with an institution like Ally Bank, which has no such language on its high-yield savings account page about a specific APY applying only to new accounts, and not existing accounts. If an Ally customer opened a new account earlier in 2026, they would earn the same rate as folks who opened an account today. In other words, any time Ally bumps up its HYSA rate, it bumps it for everyone.
When I saw EverBank raise its savings rate from 3.90% to 4.20% on Oct. 2, I didn’t receive a notification or see a change to my APY when I checked that day.
When I next checked the app, though, my rate matched the new one. I’m glad my rate went up, but since EverBank doesn’t list its baseline rate on its website, I’m unsure what will happen to my rate in these kinds of situations going forward once my account is no longer considered new. I’ve already chased savings rates at the same bank before and don’t plan to do that again.
And it was hard to find the APY at first
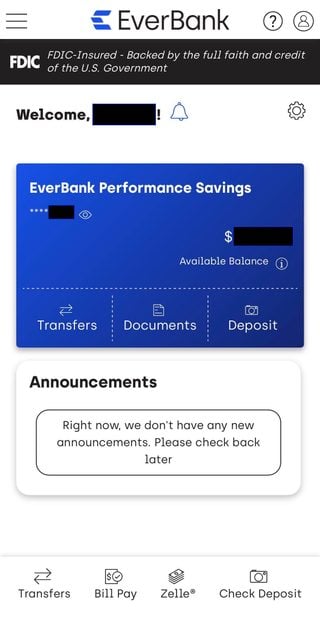
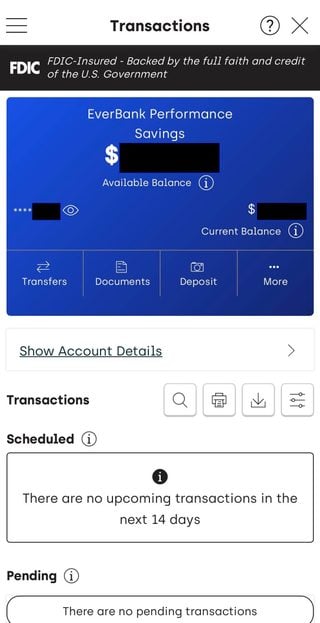
EverBank has a no-nonsense desktop and mobile design with a sliver of color and many menu options. It took a few attempts to find my current APY and interest earned, arguably the most important info for a high-yield savings account.
I tapped the account name to see more details but only saw the name and balance. A few attempts later, I tapped the underlined text “Show Account Details” that brought me to a crowded list of 14 fields from account nickname to document delivery preference. “Current APY” and “Interest YTD” (year to date) were close to the bottom. Since I’ll need to check APY often, I don’t appreciate having these multiple steps to go through.
Mobile app (iOS) views (Dashboard and account-specific)
Desktop view
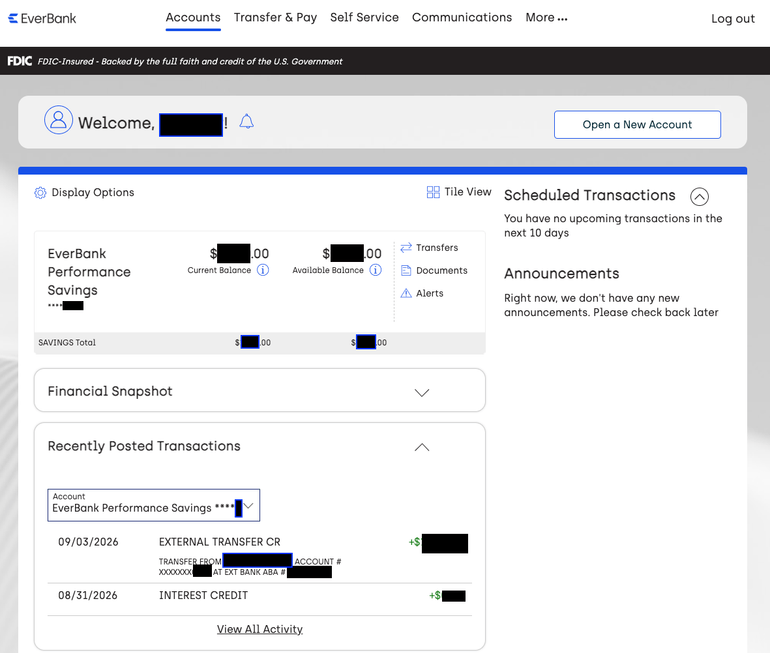
EverBank’s site and app are mostly adequate but plain
Strong security measures: When I log in to EverBank on a browser or in the mobile app, I go through two-factor authentication with a login password and code sent via text.
Decent features but lacks robust savings or budgeting tools: EverBank sticks to mostly table-stakes features: online and wire transfers, Zelle for same-day transfers with loved ones, bill pay, mobile check deposit, push notifications, and text and email alerts. The closest thing to a budgeting or savings tool was a disappointing financial snapshot that links to external accounts and only shows current balances. I didn’t see any way to create savings subaccounts, goals or customized transfer rules (such as sending a percentage of each paycheck to different accounts).
Customer support was responsive but had limited channels
Extended support hours, but not 24/7: EverBank’s main support channel is by phone, which is available from Monday through Friday, 8 a.m. to 10 p.m. ET, and Saturday, 9 a.m. to 7 p.m. ET. I live in California and these hours mostly work as long as I don’t wait to call too late or on Sunday.
No live help online: Unlike some banks, EverBank has no online live chat or messaging options.
I made two calls, both related to the APY. Each call started with a robot voice that confirmed my identity by asking for my date of birth and a 6-digit code I received via text while on the call. It took two minutes to speak to a human on a Friday afternoon and six minutes on a Monday afternoon. The representatives answered my questions clearly and to the best of their ability.
Most of my experience at EverBank, from sign-up to phone support, was positive and straightforward. But the uncertainty about my APY created a burden I haven’t encountered at a bank before. It might be enough to keep me looking for another account without this hassle.