The FICO 10 and 10T credit scores made a big splash when they were introduced in 2020, primarily because of the 10T version, which looks back over at least 24 months of credit activity to predict future credit behavior.
For the vast majority of people, however, any change to scores from the new scoring models is likely to amount to around 20 points. FICO Score 10 BNPL and FICO Score 10T BNPL, released in June 2025, represent the newest variations of FICO 10, which captures Buy Now, Pay Later data.
Here’s what to know about FICO's 10 and 10T scores.
Meet MoneyNerd, your shortcut
to smart money moves
NerdWallet's editors surface the financial moves worth thinking about this week, so you can act on them, or get on with your life. Delivered free, twice a week.
How FICO 10 and FICO 10T are different
FICO’s algorithms are analyzed and updated periodically to better predict risk. The FICO 10 update was the first time the company offered two versions of a general FICO score.
The score that got consumer attention is the FICO 10T — the T stands for trended data. If a traditional FICO score is a snapshot of your finances, FICO 10T is more like a time-lapse video of your balances and payments. FICO competitor VantageScore introduced a score using trended data, version 4.0, in 2017.
Ultimately, trended data models look at patterns in your credit reports to determine your score.
Are lenders using FICO 10 and 10T?
FICO 10 scores are available for use by the three major credit bureaus. Dave Shellenberger, vice president of product management at FICO, previously said he expected adoption by lenders would take time, and “usually longer for large lenders.”
Right now, most lenders still use the FICO 8, which was introduced in 2009, for most non-mortgage lending decisions. For mortgages, FICO 2, 4 or 5 are most used.
The Federal Housing Finance Agency (FHFA), which oversees Fannie Mae and Freddie Mac, dropped plans to require FICO 10T starting in late 2025, and hasn't set a new date. Lenders selling loans to Fannie Mae and Freddie Mac can now use VantageScore 4.0 as an alternative to Classic FICO. FICO 10T is approved but not yet eligible for loan delivery. Federal Housing Administration (FHA) lenders will be able to start using FICO 10T in January 2027.
What is FICO 10 BNPL and FICO 10T BNPL?
As consumer credit behavior evolves, so do credit score models. According to the Federal Reserve’s Survey of Household Economics and Decisionmaking, 16 percent of adults obtained a BNPL loan in 2025.
Most BNPL loans don’t appear on consumer credit reports and, as a result, they remain largely invisible to lenders, who historically couldn’t see if potential applicants had taken out more BNPL loans than they could handle. On the other hand, consumers’ on-time BNPL payments weren’t being recorded by credit bureaus either.
In its 2025 BNPL study, FICO simulated how adding buy now, pay later (BNPL) account data could affect credit scores. Most scores changed only slightly: 85% of BNPL customers saw changes of less than 10 points. Among those with five or more BNPL accounts, 97% saw changes of less than 20 points. This could be good news for consumers who are trying to build their credit but also rely on BNPL for important purchases.
FICO launched the BNPL models in 2025 and plans to offer them alongside existing FICO scores. But FICO says they'll be available at the credit bureaus when BNPL data is more widely available.
How might FICO 10 affect your score?
Your score is most likely to drop when using the FICO 10 scoring models if:
You took out a personal loan to consolidate credit card bills, but now your card balances are up again or it appears you have applied for additional credit.
You are using credit cards to get by — and you just can’t seem to whittle the balances down or your balances are growing.
You have missed a payment. The penalty for going 30 days past due will be even harsher than it is under previous FICO scoring models.
On the other hand, some people could see their scores rise by 20 points or more. Your score is most likely to rise if you have been penalized for occasional high balances. Shellenberger gave an example: If you typically vacation in July and put airline tickets, hotel and meals on a credit card — and then pay it off — the trended data won’t penalize you as much. It looks at balances over time and sees you bringing a temporarily high balance down.
Keys to a higher score on the FICO 10 and 10T
Pay down balances on credit cards. Consistently high statement balances — or rising balances — can suggest financial difficulty. If you are paying off your bills monthly but have high statement balances, make frequent payments throughout the month. That keeps your balance low no matter when it’s reported to the credit bureaus.
Do all you can to avoid missing a payment.
If you don’t already have an emergency fund, start one. If you have to turn to credit cards in an emergency, your rising balances could hurt your scores.
If you are thinking of consolidating credit card debt with a personal loan, avoid charging up the credit card balances again; FICO 10T will penalize you for it.
How to look good no matter what score lenders use
Make no mistake: Lenders want to find creditworthy applicants. They just want to minimize the risk that they’ll approve customers who won’t pay as agreed.
The ways to build credit have not changed:
Pay every bill on time.
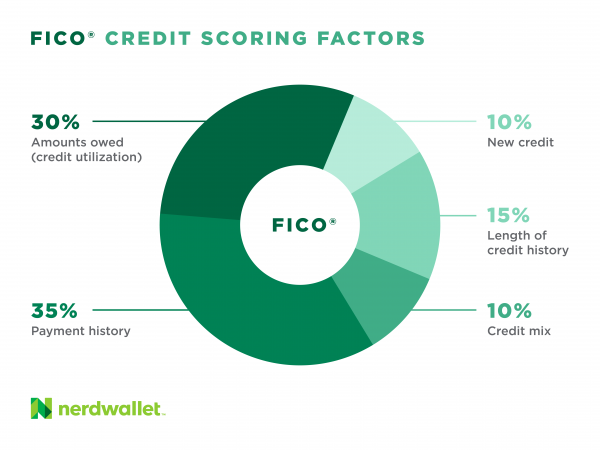
Keep credit card balances low relative to your credit limits, which benefits a highly influential scoring factor called credit utilization.
Be judicious about applying for new credit. A flurry of new applications can suggest financial distress.
Keep old credit card accounts open unless you have a compelling reason to close them, such as a high annual fee. Their credit limits help your credit utilization and older cards also contribute to credit age, a minor factor in your score.
Article sources
- 1.Federal Reserve Board. Survey of Household Economics and Decisionmaking. Accessed Nov 3, 2026.
- 2.FICO. Buy Now, Pay Later Study. Accessed Nov 3, 2026.
- 3.FICO. Modernizing Credit Scoring for the BNPL Era. Accessed Nov 3, 2026.