

Every time.
We believe everyone should be able to make financial decisions with confidence. While we don't cover every company or financial product on the market, we work hard to share a wide range of offers and objective editorial perspectives.
So how do we make money? Our partners compensate us for advertisements that appear on our site or when you click to or take an action on their website. This compensation helps us provide tools and services - like free credit score access and monitoring. With the exception of mortgage, home equity and other home-lending products or services, partner compensation is one of several factors that may affect which products we highlight and where they appear on our site. Other factors include your credit profile, product availability and proprietary website methodologies.
However, these factors do not influence our editors' opinions or ratings, which are based on independent research and analysis. Our partners cannot pay us to guarantee favorable reviews. Here is a list of our partners.
Venmo Credit Card Review: Up to 4% Back, If You Split the Tab

The Bottom Line
3.4
It can make a lot of sense for frequent Venmo users, considering how ubiquitous that payment platform is. But plenty of other cards can be just as lucrative, if not more so — with or without using Venmo.
Rates, fees and offers
Rates, fees and offers
Annual fee
$0
Rewards rate
1%-4%
Bonus offer
None
Intro APR
N/A
Ongoing APR
APR: 18.74%-30.74% Variable
Cash Advance APR: 30.74%, Variable
Foreign transaction fee
0%
More details from Synchrony Bank
More details from Synchrony Bank
- Earn up to 4% cash back on eligible purchases: Earn 3% cash back on dining and entertainment purchases, which includes streaming. Earn an extra 1% when you split the purchase with a friend on Venmo.
- Earn 3% cash back when you check out with Venmo online, pay a business on Venmo, or pay someone for goods or services on Venmo.
- Earn 1% cash back on all other purchases.
- No annual fee.
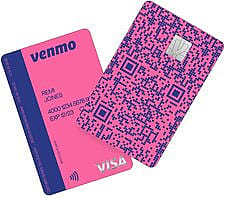
- Your card comes with your own unique QR code on the front, so it’s a snap to Venmo friends. When they scan your code, up pops your Venmo profile to pay or get paid.
- Keep tabs on card activity in the app, right with all your Venmo spending.
- Use the Venmo app to disable a lost or stolen physical card.
Pros and Cons
Pros
No annual fee
Bonus categories
Cons
No 0% intro APR
Requires good/excellent credit
Detailed Review
The investing information provided on this page is for educational purposes only. NerdWallet, Inc. does not offer advisory or brokerage services, nor does it recommend or advise investors to buy or sell particular stocks, securities or other investments.
• • •
The Venmo Credit Card, issued by Synchrony Bank, stays true to Venmo’s roots as an app that makes it easy to split costs between friends. It rewards you well for purchases made through the payment platform, and its design even features a QR code that others can scan with their phones — so when you front the cost of a restaurant meal with your card, you won’t need to chase anyone down to get paid back.
Of course, if you aren't interested in actually using Venmo, the Venmo Credit Card is not for you. It's also worth noting that the card tends to change its welcome bonus quite often (assuming it happens to be offering one at all).
Eligible Venmo customers can apply for the card through the Venmo app, but you must have had a Venmo account for 30 days first.
» MORE: What is Venmo?
The Venmo Credit Card launched in 2020 with a unique, customizable 3%/2%/1% rewards structure. As of September 2026, the card moved to a new and more traditional rewards structure that's described in this review. But existing cardholders were not required to transition to the new version and were able to retain the card's original rewards structure if they wanted to.
Venmo Credit Card: Basics
Card type: Cash back.
Annual fee: $0.
Sign-up bonus: This card occasionally offers bonuses for new applicants that may change over time.
Rewards:
3% cash back on dining and entertainment, including streaming. (You can get an extra 1% back — for a total of 4% cash back in these categories — when you split the transaction and get paid back in the app.) Terms apply.
3% cash back when you pay with Venmo.
1% cash back on all other purchases.
Cash back rewards may be applied as a credit toward your bill. Your can also transfer the cash back to another Venmo account, linked bank account or debit card. Cash back may also be used to make purchases with Venmo or to buy cryptocurrency.
Interest rate: The ongoing APR is 18.74%-30.74% Variable.
Foreign transaction fees: None.
Minimum redemption requirement: None.
Compare to Other Cards
Benefits and Perks
Solid rewards for heavy Venmo users
As you might expect, the Venmo Credit Card incentivizes the use of its namesake app, earning 3% cash back when you pay with Venmo. You'll also earn up to 4% back on eligible dining and entertainment when you split those transactions and get paid back in the app. Otherwise, you still earn a 3% rate in those categories.
Wide range of redemption options
Any cash back you earn will appear in your Venmo balance after your statement closes. Once earned, you can apply the money toward a credit card bill (much like a statement credit), make purchases from a merchant that accepts Venmo, send money to someone else through the Venmo app, or transfer it to a linked bank account or debit card.
Cash back may also be used to buy certain cryptocurrencies through the Cash Back to Crypto redemption option. If you opt-in to the auto-purchase feature, any cash back in your account will automatically be used to purchase the cryptocurrency of your choice — without incurring a crypto transaction fee.
» MORE: Best crypto credit cards
Unique card design that makes splitting costs simple
Each physical card features its own QR code on the front, which comes in handy when you’re splitting a purchase with another person. They can scan the QR code from the Venmo app and be brought to your Venmo profile. From there, they can send money, or request money from you. Keep in mind that paying a friend over Venmo using the Venmo Credit Card means you’ll pay a 3% fee, which is the same as using any other credit card for peer-to-peer transactions.
Gettable with fair credit
Many top rewards credit cards require at least good credit, meaning FICO scores from the mid-600s or upward. But the Venmo Credit Card is attainable with only fair credit, which typically corresponds to FICO scores from the mid-500s to low 600s. That's a relatively under-served market for credit cards, especially ones that earn decent rewards.
Instant access upon approval
While your physical card is in the mail, you can begin making purchases with the virtual version of the card, which lives within the Venmo app and can also be added to digital wallets. Once the physical card arrives, you can activate it by scanning the QR code.
Manage the card via the Venmo app
If you need to pay your balance, see your rewards activity, change notifications, set up autopay, or track your spending trends or transactions, you'll do so through the Venmo app. If your physical card is lost or stolen, you can disable it in the app and continue to shop with the virtual card. There’s no separate website to log into. (For some, this may count as a drawback; see below.)
Drawbacks and Considerations
Best rewards have strings attached
Yes, the card earns up to 4% back on dining and entertainment, an excellent rate for a no-annual-fee card. But getting the full 4% is contingent on splitting each eligible transaction within the Venmo app. You must also be paid by your fellow Venmo users for the transaction within 30 days of purchase. Meeting both of those requirements nets you an additional 1% on top of the base 3% dining and entertainment rewards rate.
Surely you’re not going to split every restaurant bill or movie ticket purchase, meaning that some (most?) of your purchases will earn 3% rather than 4% back. And the idea of your rewards-earning potential being contingent on another’s ability to pay you back is sure to turn off some consumers.
Welcome bonus is a moving target
The Venmo Credit Card currently offers bonuses on a limited-time basis. So if you want the bonus, you'll have to time your application carefully. Other cards consistently sweeten the deal with welcome offers worth $150 or more, which can help offset the annual fee some of them charge. One example is the Blue Cash Preferred® Card from American Express, which offers this welcome bonus: You may be eligible for as high as $300 cash back after spending $3,000 in purchases on your new Card in the first 6 months. Welcome offers vary and you may not be eligible for an offer. Cash back is received as Reward Dollars, redeemable for statement credit or at Amazon.com checkout. Terms Apply. The card also earns generous cash-back rates in several common spending categories. It charges a $0 intro annual fee for the first year, then $95.
You must use it with the Venmo app
There’s no Venmo Credit Card without the Venmo app. All aspects of card management — paying balances, redeeming rewards, changing notifications, setting up autopay and locking the card — must occur within the app. There’s no separate website to log into on a desktop, for example.
If you don’t want to use the Venmo app and prefer a more traditional credit card experience, other cash-back credit cards would be a better fit.
How To Decide If It's Right For You
If you already use Venmo and you want an easy-to-manage card with decent ongoing rewards, the Venmo Credit Card could certainly be a contender. The card’s seamless user experience makes it feel futuristic and fresh.
But if you’re after a lucrative welcome bonus or you have no desire to use Venmo as a payment tool, you'll want to look elsewhere.
See how this card stacks up with NerdWallet's best credit cards to get.
To view rates and fees of the Blue Cash Preferred® Card from American Express, see this page.
Earn more in popular categories
Earn 6% cash back at U.S. supermarkets on up to $6,000 in spending per year, 6% cash back on select U.S. streaming services, 3% cash back at U.S. gas stations and on transit, and 1% back everywhere else. There's a $0 intro annual fee for the first year, then $95 Terms apply.
Looking For Something Else?
Methodology
NerdWallet reviews credit cards with an eye toward both the quantitative and qualitative features of a card. Quantitative features are those that boil down to dollars and cents, such as fees, interest rates, rewards (including earning rates and redemption values) and the cash value of benefits and perks. Qualitative factors are those that affect how easy or difficult it is for a typical cardholder to get good value from the card. They include such things as the ease of application, simplicity of the rewards structure, the likelihood of using certain features, and whether a card is well-suited to everyday use or is best reserved for specific purchases. Our star ratings serve as a general gauge of how each card compares with others in its class, but star ratings are intended to be just one consideration when a consumer is choosing a credit card. Learn how NerdWallet rates credit cards.
About the author
Sara Rathner
Senior Writer/Spokesperson
