






A 529 is a tax-advantaged college savings account that can be used to pay for a beneficiary’s qualified education expenses, such as tuition or textbooks. While it was originally limited to higher education, the funds can now also be used for tutoring, test fees, educational therapies, credentialing programs and K-12 expenses.
How do I find the best 529 plan?
Consider your in-state plan first
Unlike retirement and other investment accounts, 529 savings plans are typically operated by states. Most states offer a tax deduction for contributing, and some even offer credits. Several states even have what's known as parity, where you get a deduction just for contributing to a 529, even if it's through another state's plan.
As you're evaluating the tax benefits, make sure to scrutinize the details, too. There may be income restrictions on the tax deduction/credit, which means that if you make over a certain amount, you might not be able to take advantage. You'll also want to understand the recapture rules, especially if you plan to move. Sometimes changing a plan or moving to another state can trigger having to repay deductions you took.
Another thing to consider is whether you can carry over excess deductions into future years. Let's say you are only able to deduct $2,000 worth of contributions per year, but you made $8,000 — some states let you continue deducting the difference on future year tax returns while others do not.
Quick Facts
Tax parity: Nine states — Arizona, Arkansas, Kansas, Maine, Minnesota, Missouri, Montana, Ohio and Pennsylvania — offer tax parity, meaning that if you live in one of them but contribute to another state's 529 plan, you can still take a deduction on your state income tax return.
No state income tax benefit: Alaska, California, Florida, Hawaii, Kentucky, Nevada, New Hampshire, North Carolina, South Dakota, Tennessee, Texas and Washington do not currently offer residents a tax credit or deduction for 529 contributions.
Unlimited tax deductions: Generally, states let you deduct only up to a certain limit of your contributions. Residents of New Mexico, South Carolina and West Virginia who invest in their state's plan can deduct the full amount they contribute each year.
When an out-of-state plan might make sense
For many people, a state plan may be the best choice. But you’re free to choose any plan you’d like. In fact, it may be prudent to examine your options in some cases, according to Jake Faucett, a Chicago-based certified financial planner at Moneta.
If any of these four factors apply to you, it may be worth taking a look beyond state lines:
If your state doesn't offer a tax deduction. This one is a bit of a no-brainer. If your state doesn't offer any incentives, feel free to shop around nationally, Faucett said in an email interview.
If you have the money earmarked for a specific purpose. Even though the federal government has expanded what 529 plans can be used for (read more on 529 plan rules), some states don't honor federal rules. For example, New York doesn't consider funds used for K-12 expenses as qualified withdrawals even though the federal government does, which can mean you'll be on the hook for income taxes and fees if you wanted to dip into your funds for those purposes.
If you think you might be moving to another state soon. Sticking with a state plan that has a small deduction may not make sense if you think you'll be moving soon, said Faucett. The benefit may be minimal, and you might also have to deal with recapture — that tricky tax rule we mentioned earlier.
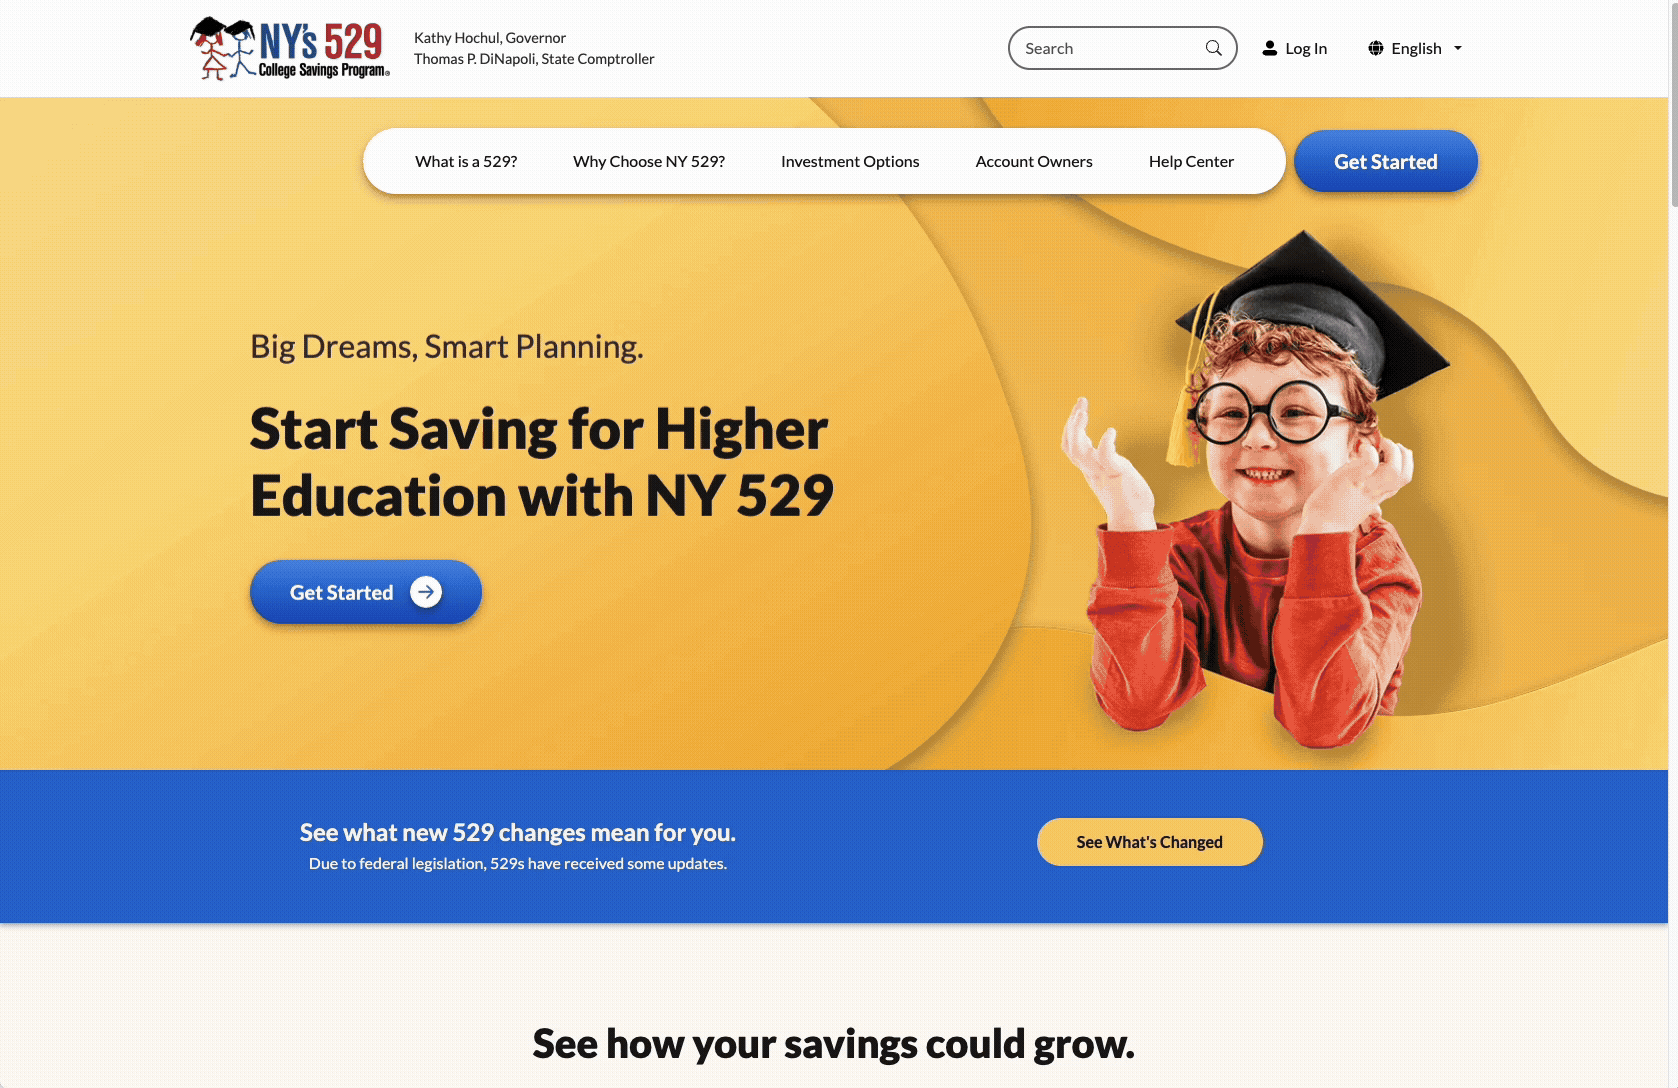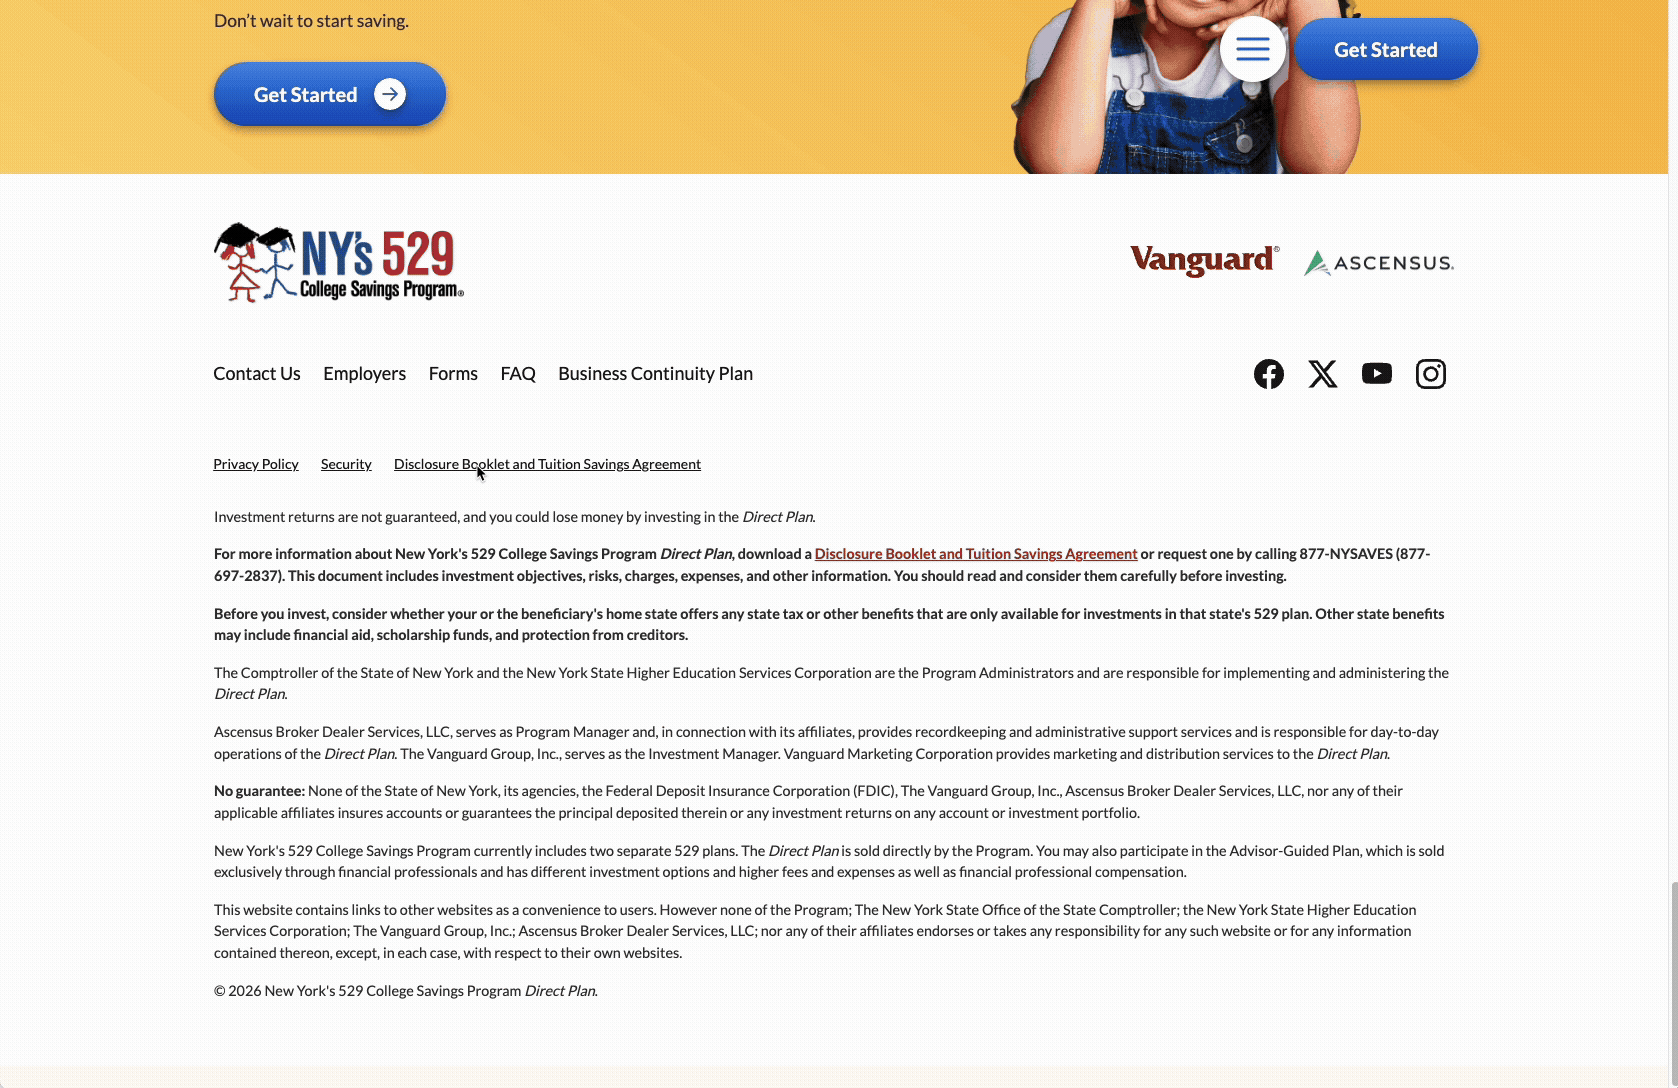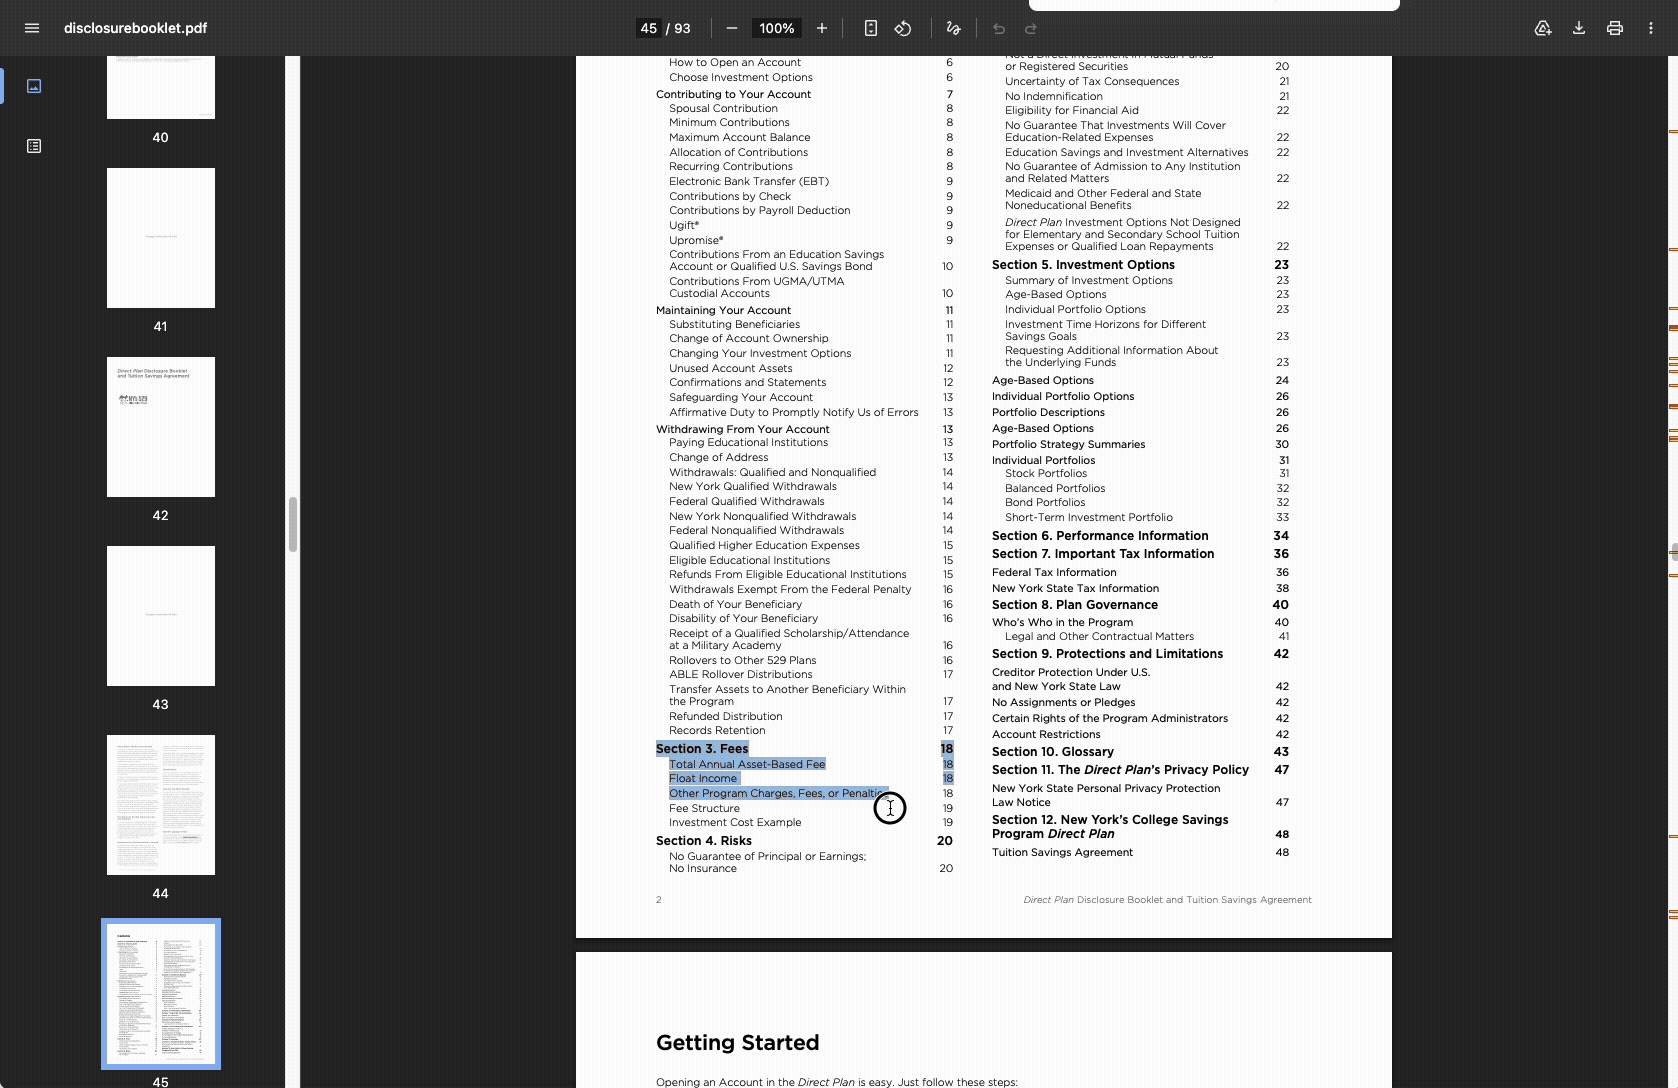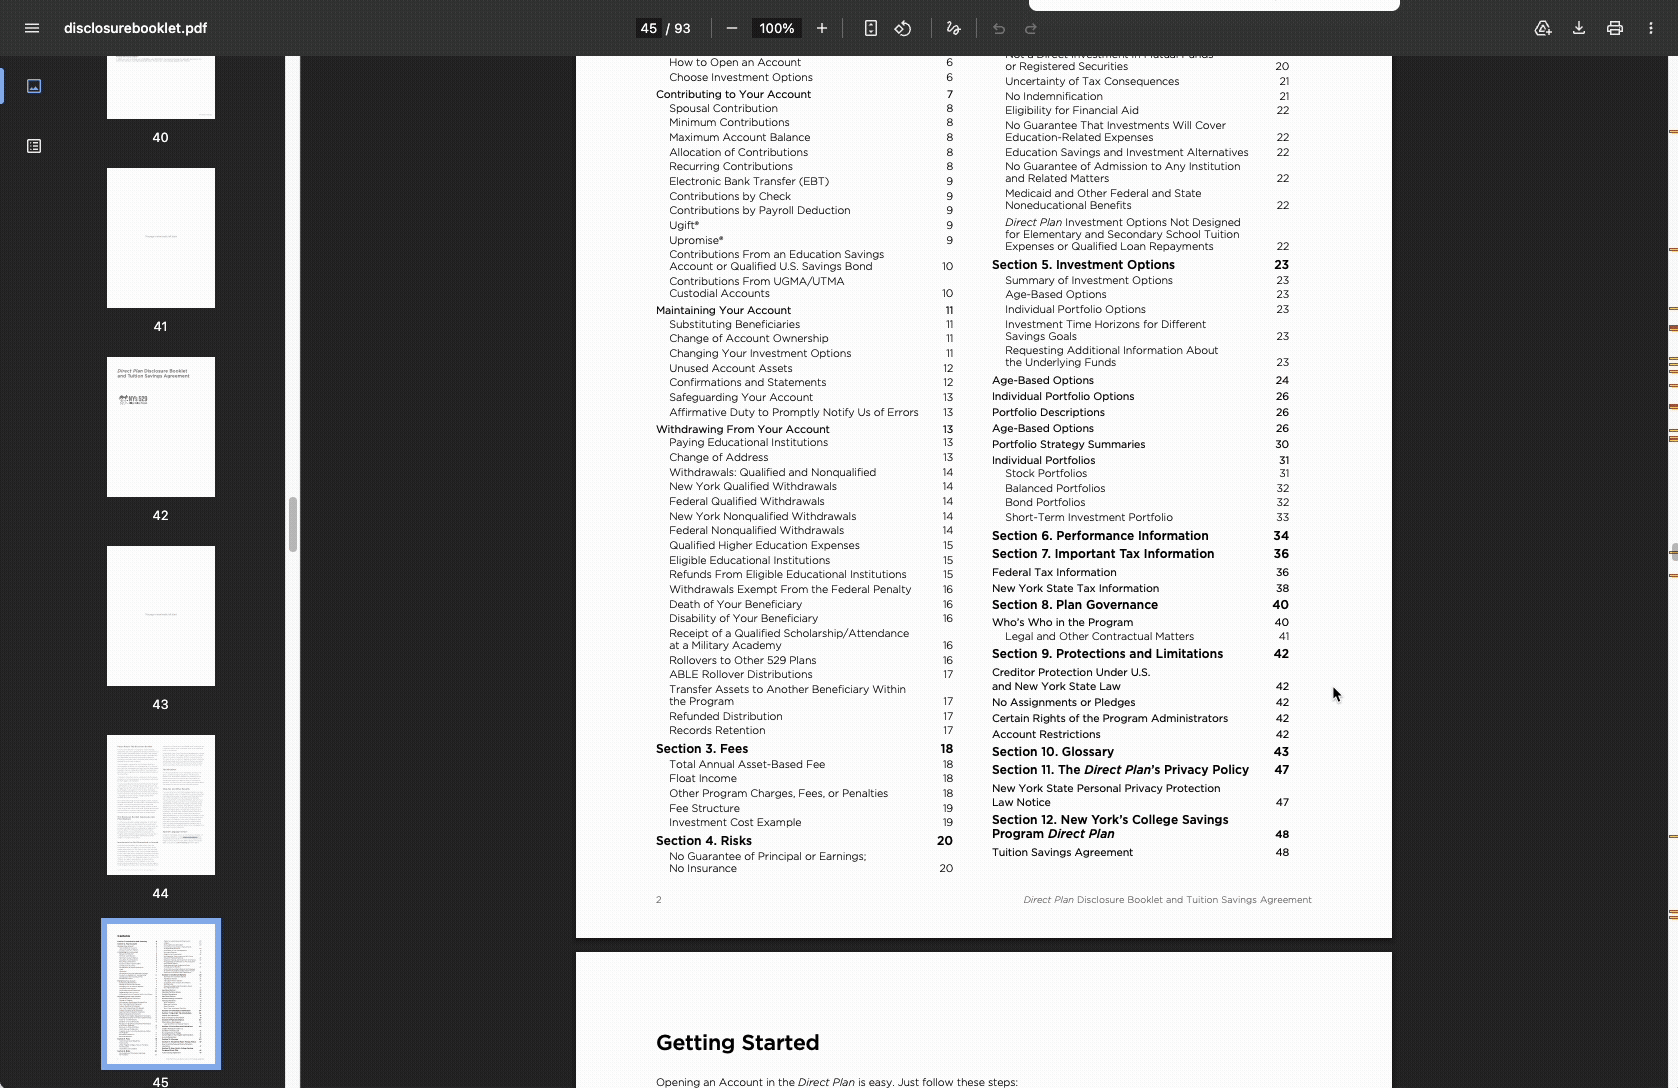
If your state plan has high fees or poor performance. Some plans have higher investment and maintenance fees than others — or they might just have a poorer performance history. "A mediocre plan with a small tax break doesn’t provide the same long-term benefit as a best-in-class out-of-state plan over 10-18 years of investment compounding," according to Faucett. If you want to take a deeper look at a plan's fees and performance history, you should be able to find a plan program or disclosure statement on your state's 529 website — typically toward the bottom of the site.
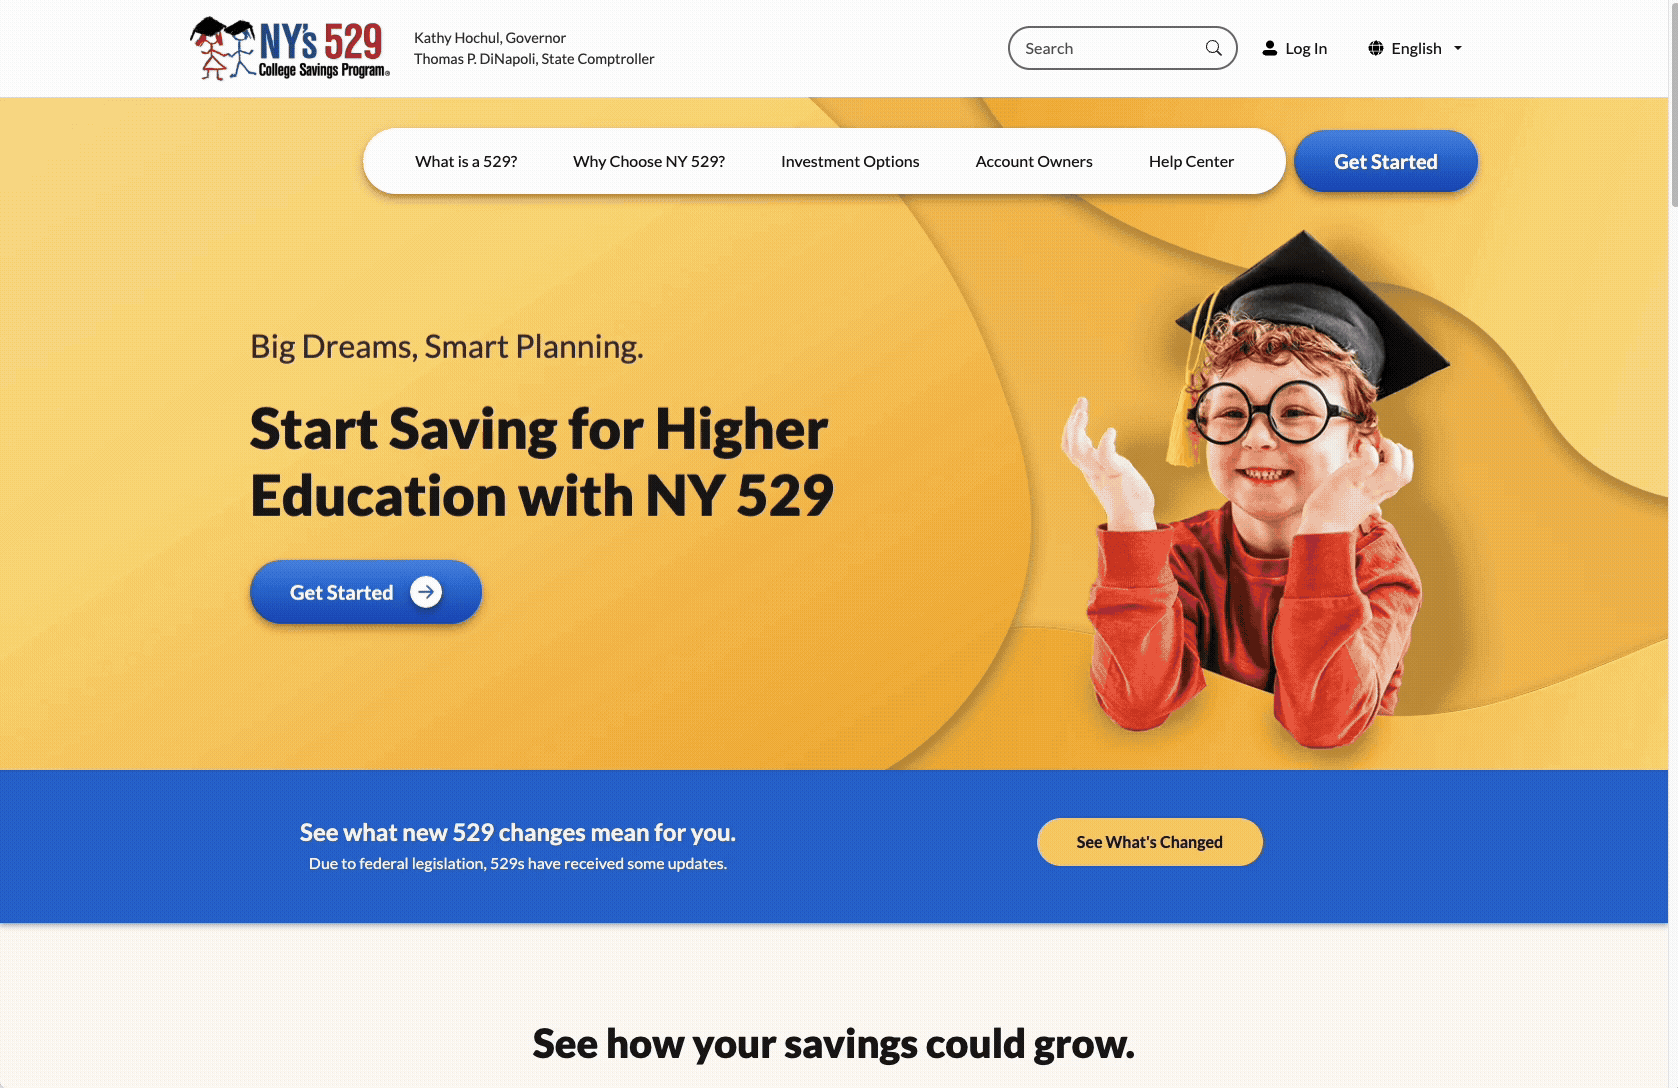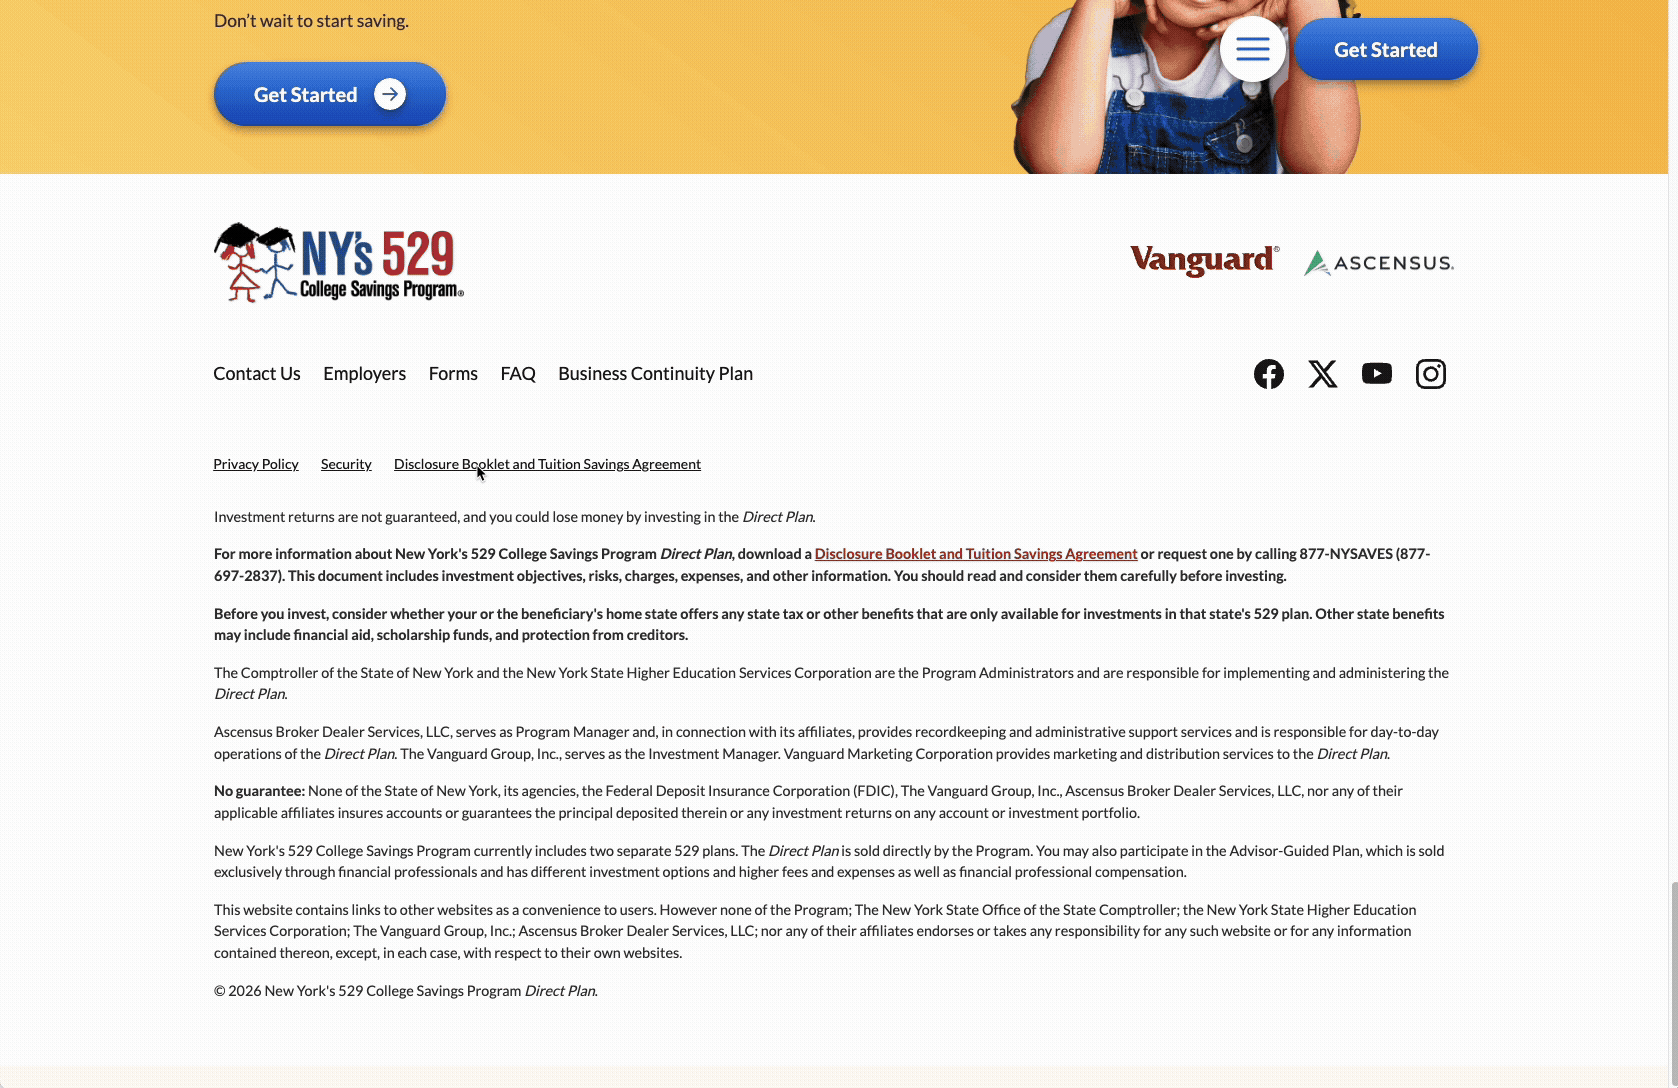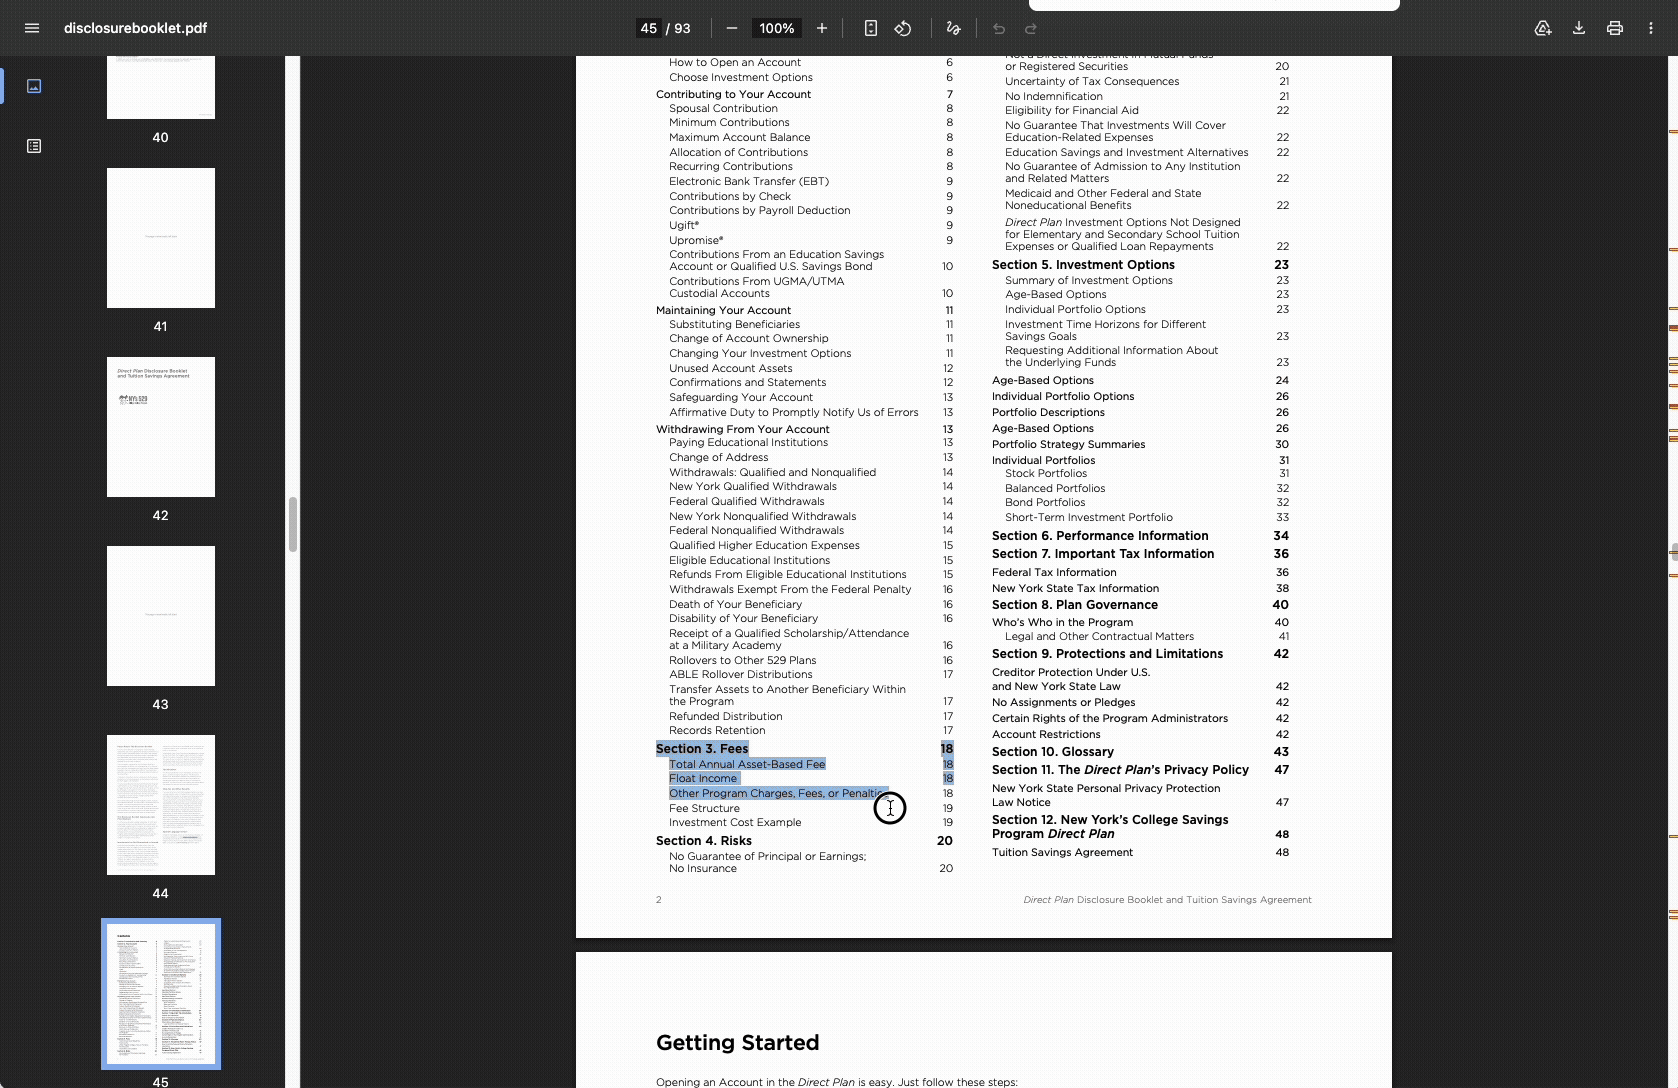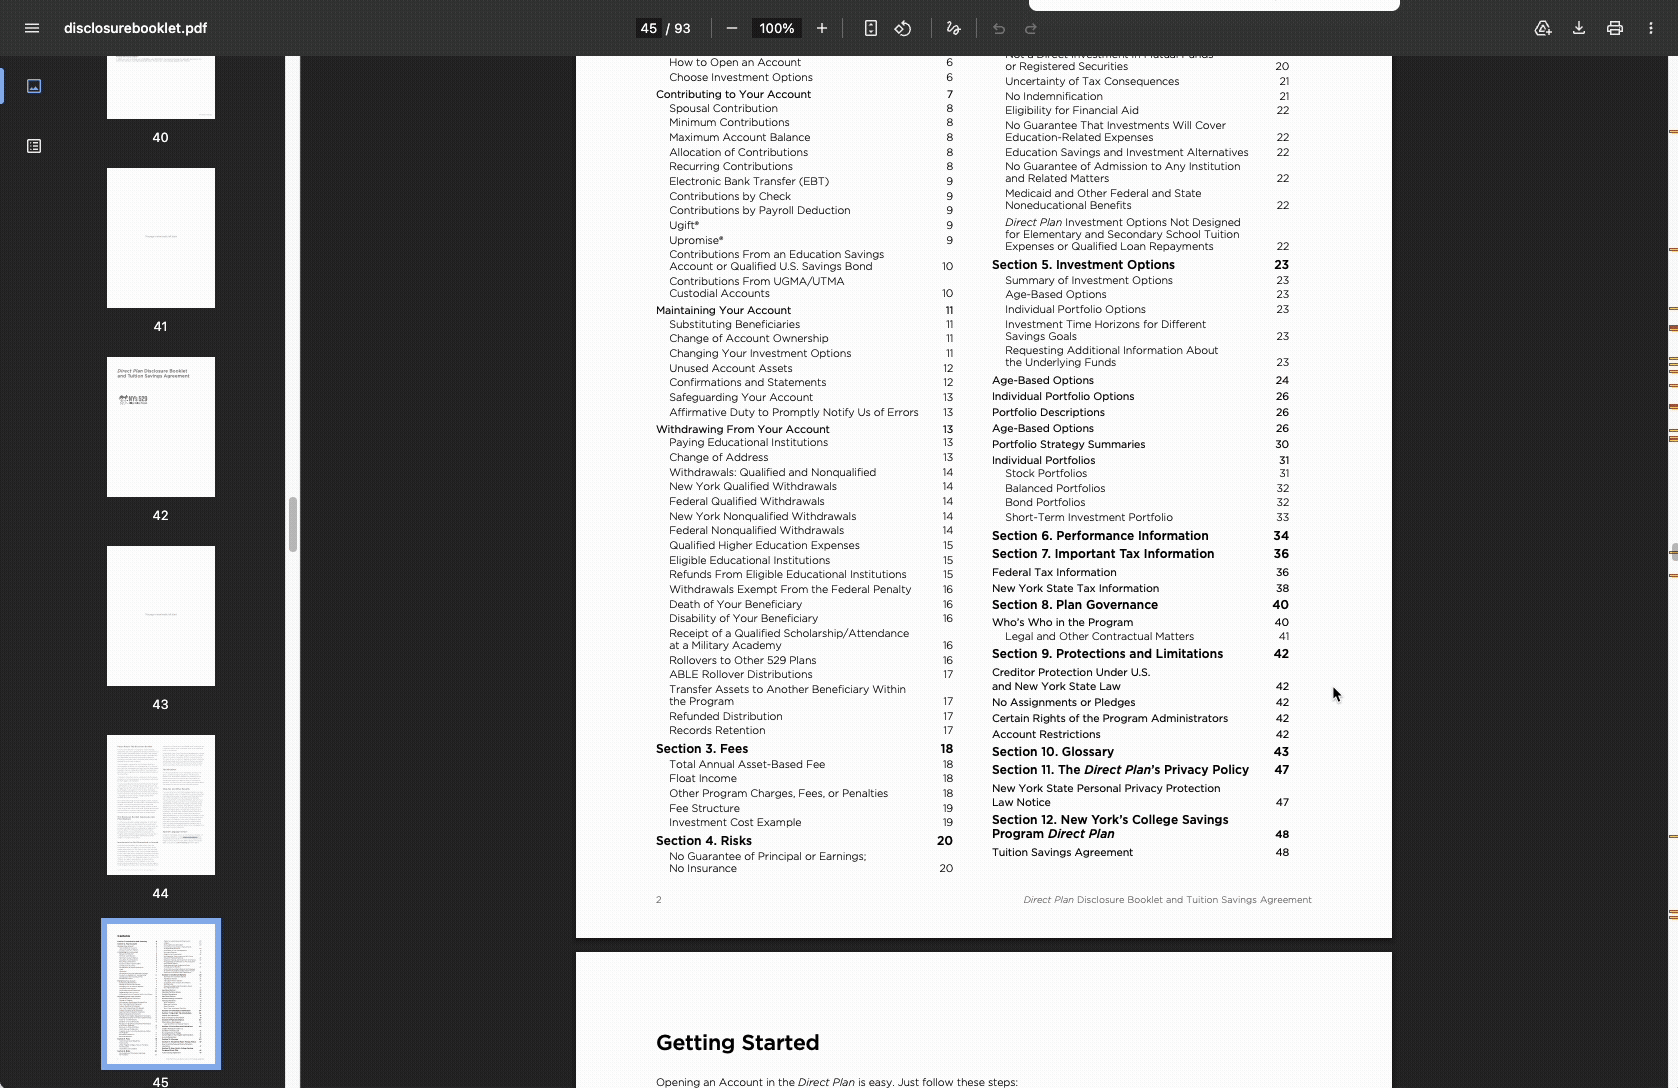
529 plans by state
There are two main types of 529 plans:
529 prepaid plans let you prepay part or all of in-state public tuition, locking in the tuition at the time of payment.
529 college savings plans are the most common type and generally considered the best and most flexible 529 option. Investments grow tax-free for qualified educational expenses.
Search by state
Would you prefer to see this data as a table? Click here ↓
State | Plan Name | Tax benefit for in-state contributors? | Minimum contribution |
|---|---|---|---|
Alabama | Yes | $0 | |
Alaska | No | $25 | |
Arizona | Yes | $15 or less | |
Arkansas | Yes | $25 | |
California | No | $0 | |
Colorado | Yes | $0 to $25 depending on plan | |
Connecticut | Yes | $0 | |
Delaware | Yes | $100 | |
District of Columbia | Yes | $25 | |
Florida | No | $0 | |
Georgia | Yes | $25 | |
Hawaii | No | $15 | |
Idaho | Yes | $25 | |
Illinois | Yes | $0 | |
Indiana | Yes | $10 | |
Iowa | Yes | $25 | |
Kansas | Yes | $0 | |
Kentucky | Yes | $0 | |
Louisiana | Yes | $10 | |
Maine | Yes | $25 | |
Maryland | Yes | $25 | |
Massachusetts | Yes | $0 | |
Michigan | Yes | $25 | |
Minnesota | Yes | $25 | |
Mississippi | Yes | $25 | |
Missouri | Yes | $0 | |
Montana | Yes | $25 | |
Nebraska | Yes | $0 | |
Nevada | No | Depends on plan | |
New Hampshire | No | $0 | |
New Jersey | Yes | $25 | |
New Mexico | Yes | $0 | |
New York | Yes | $0 | |
North Carolina | No | $25 | |
North Dakota | Yes | $25 | |
Ohio | Yes | $25 | |
Oklahoma | Yes | $25 | |
Oregon | Yes | $25 | |
Pennsylvania | Yes | $0 | |
Rhode Island | Yes | $0 | |
South Carolina | Yes | $0 | |
South Dakota | No | $50 per portfolio | |
Tennessee | No | $25 | |
Texas | No | $25 | |
Utah | Yes | $0 | |
Vermont | Yes | $25 | |
Virginia | Yes | $10 | |
Washington | No | $1 | |
West Virginia | Yes | $0–$50 depending on plan | |
Wisconsin | Yes | $25 | |
Wyoming | No plan available | — | — |
Figures as of July 22, 2026, for informational purposes only. Source: State 529 plan websites. | |||
The bottom line
According to Faucett, the decision comes down to weighing tax benefits against plan fees and investment quality: "If your state's deduction is modest and the in-state plan has noticeably higher fees or a weaker investment lineup, the math often favors going out of state. However, if your state's deduction is generous, it's harder for an out-of-state plan to make up the difference."
Article sources
- 1.New York's 529 College Savings Program . SUPPLEMENT DATED OCTOBER 2025, TO NEW YORK’S 529 COLLEGE SAVINGS PROGRAM DIRECT PLAN DISCLOSURE BOOKLET AND TUITION SAVINGS AGREEMENT DATED SEPTEMBER 30, 2021. Accessed Jul 28, 2026.