


I’m not one to chase rates on my savings, but seeing my annual percentage yield wilt this past year had me on the lookout for a new account. I work on NerdWallet’s banking team, so I didn’t have to look far.
I saw E*TRADE from Morgan Stanley Private Bank — which is consistently on our list of best high-yield savings accounts — was offering a $400 bonus on its Premium Savings Account and a guaranteed rate for six months. The time felt right to try a new account.
» Want a bonus, too? See our list of best bank account bonuses to learn more
What I initially liked about the account
The Premium Savings Account has a lot of what we at NerdWallet look for in a good savings account, including no monthly fees, a highly-rated app and a high rate. The base annual percentage yield at the time I opened the account was half a percentage point higher than what I was earning in my current account (3.50% versus 3%). Now the difference is even bigger. E*TRADE also offered a boosted yield of 4% for six months, if I met the requirements (which I did). The promise of a fixed rate on a savings account was enticing, since savings accounts normally have variable APYs that can change at any time.
» Is a new account worth it for you? See what you can earn with our compound interest calculator
The boosted rate at E*TRADE is kind of like opening up a certificate of deposit, without the restrictions.
With a certificate of deposit, you lock in a rate for the duration of the certificate’s term. As a trade-off for this guarantee, you agree to not withdraw the funds for the term, too (or pay a penalty if you do). So locking in a rate for six months when I opened the account in mid-August felt like a win — like I opened a CD but my funds were still liquid. But it turned out to be a bit of a miss for me, as E*TRADE raised its APY after the Federal Reserve’s rate hike in mid-September. If I had opened the account about six weeks later, I’d be earning 4.25% APY for six months instead of 4%. I’m only losing out on about $25 in interest but I called E*TRADE to see if they’d bump my boost APY anyways.
Alas, I was told I’d have to open a new account to get that rate.
» Did your savings yield go up? See why and how the Fed affects your savings rate
Opening the account was easy
Opening the account was an overall good and easy experience. The one hiccup was the limited number of professions to choose from in the drop-down menu to describe my job. I spent more time on this than I did on the rest of the application and I have no idea if it mattered at all. I wish there had been an option to just choose “Other.”
Transfer times were slower than what I want
I connected my other savings account seamlessly and initiated an ACH transfer right away (though I didn't need to since the account has no minimum opening deposit). The transfer took three business days to complete.
I scheduled another transfer to test this again since the first transfer into a new account can sometimes take longer than usual.
- I set up the transfer on Monday night (past the 4 p.m. ET cut-off time).
- I started earning interest on the money on Wednesday.
- But the funds weren’t available for withdrawal until Friday. That’s three full business days again.
The bank was upfront about how long it would take on the transfer set-up screen so I wasn’t surprised, but I was disappointed.
If I had needed that money earlier in the week, I would have been out of luck.
This isn’t all on E*TRADE, though. I can (and did) instantly transfer money into the Premium Savings Account from a different account (a Chase checking account), because Chase offered that option.
E*TRADE does provide one faster option: wire transfers. It’s free to receive a wire here, but it’s not necessarily free to send one from the originating bank. And for outgoing wire transfers, E*TRADE charges $25 a pop. I’m not interested in that. I just want easy, free access to my emergency funds at a moment’s notice.
» Need a wire transfer? See what banks charge
There is another workaround to make quick, free transfers out of the account. I could open a checking account with E*TRADE from Morgan Stanley, because that would allow me to instantly transfer money from my savings to checking and then use Zelle to move money out same-day, but I’m not looking to switch my checking or have to manage yet another account.
The logged-in app experience was good but focused on investing
It was easy to find all the bank details I cared about the most in the logged-in app and desktop experience — available balance, total balance, interest earned and APY. They’re all front and center, which isn’t something I can say for my other bank accounts. It’s nice to always be able to see your progress and check on your rate.
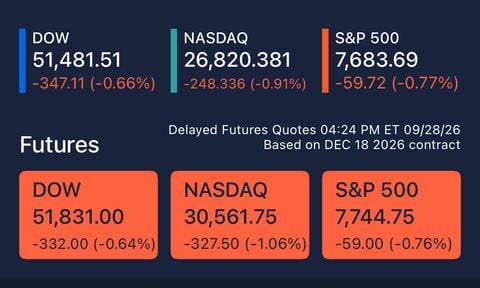
But the app experience is focused on investing, which I should have expected given E*TRADE’s focus. I just thought since I was opening a savings account and not a brokerage account, I wouldn’t see so much investing info. But when I log in to see my savings account info, the homepage shows me numbers for the DOW and NASDAQ and S&P 500, and even futures. When everything is red, it’s quite a bleak thing to encounter when you’re just trying to check on your savings.
I’m keeping the account, but not for what I initially thought
All in, the Premium Savings Account is a solid account. I’m keeping it open to hold my non-emergency savings because I like the rate, the transparency of the information in the app and how quick the bank was to raise its rate after the Fed announcement. But I want quicker access to emergency funds than my savings-only set up at E*TRADE can get me.
I’ll be considering a cash management account or a money market account for my emergency stash since these accounts are more likely to give me the instant access I crave while paying high rates.
» Curious about these accounts? See our list of the best cash management accounts and best money market accounts