



A comprehensive and well-written business plan can improve your chances of getting approved for a small-business loan. Many lenders require it, and it’s your chance to show them why your business is worth investing in.
How much do you need?
What does a business plan include?
A successful business plan for a loan describes your financial goals and how you’ll use borrowed funds to achieve them. It can run 20 to 30 pages, and both established businesses and startups can benefit from writing one.
Although business plans vary from company to company, there are a few common sections included in most plans.
Here are the core elements:
Executive summary: The elevator pitch summarizing your plan.
Company overview: Your business’s background and what sets it apart.
Products and services: What you sell and how it benefits customers.
Market analysis: An overview of your industry, customers and competitors.
Marketing and sales plan: How you’ll attract customers and make sales.
Operational plan: What it takes to run your business smoothly.
Management team: Who runs your business and their qualifications.
Funding request: How much you need, its purpose and repayment plan.
Financial statements: Your business’s financial history and future projections.
Appendix: Supporting documents that strengthen your business plan.
Executive summary
This is the first (and often most important) part of your plan that lenders read.
The executive summary serves as an elevator pitch for your company and loan request. When done correctly, it sparks interest in your business.
It includes:
High-level information about you, your products and services.
Your management team, employees, business location and financial details.
Your mission statement.
How much funding you need and how you plan to use it.
To help build a lender’s confidence in your business, include a breakdown of your growth plans here.
Company overview
The company overview describes your business in more detail and highlights its strengths. If you didn’t explain what problems your business solves in the executive summary, do it here.
Highlight:
Specific details about your business such as when it was founded, your business entity type and history.
Any experts on your team and relevant professional relationships (e.g., your accountant or a business advisor).
What gives you a competitive advantage (e.g., a convenient location or specialized expertise).
Key milestones you’ve reached, such as opening a second location or expanding your customer base.
Products and services
Use this section to demonstrate the need for what your business offers. Describe your products and services and explain how customers use and benefit from them.
Detail any equipment or materials that you need to provide your goods and services — this may be particularly helpful if you’re looking for equipment or inventory financing. You’ll also want to disclose any patents or copyrights in this section.
Market analysis
Here you can demonstrate that you’ve done your homework and showcase your understanding of your industry, current outlook, trends, target market and competitors.
You can add details about your target market that include:
Where you’ll find customers.
Ways you plan to market to them.
How your products and services will be delivered to them.
How often they might buy your product or service.
Whether there will be seasonal peaks or steady demand.
Marketing and sales plan
Your marketing and sales plan provides details on how you intend to attract customers and build a client base. You can also explain how your product or service is sold and delivered.
At a high level, this section should identify your sales goals and how you plan to achieve them — for example, through advertising, PR, trade shows, etc. This shows a lender how you’re going to make money to repay your debt.
Operational plan
The operational plan covers the physical requirements of operating your business on a day-to-day basis.
Depending on your type of business, this may include:
Location.
Facility requirements.
Equipment.
Vehicles.
Inventory needs and supplies.
Production goals, timelines, quality control and customer service details may also be included in this section.
Management team
This section illustrates how your business will be organized. You can list the management team, owners, board of directors and consultants with details about their experience and the role they will play at your company. This is also a good place to include an organizational chart.
From this section, a lender should understand why you and your team are qualified to run a business and why they should feel confident lending you money — even if you’re a startup.
Funding request
In this section, you’ll explain:
The amount of money you’re requesting.
Why you need it.
The type of financing you want (e.g., term loan or business line of credit).
How long you need to pay it back.
How you’ll use the funds.
How you plan to pay it back.
You may also discuss any funding requirements you anticipate over the next five years and your strategic financial plans for the future.
Financial statements
When you’re writing a business plan for a loan, this is one of the most important sections. The goal is to use your financial statements to prove to a lender that your business is stable and will be able to repay any potential debt.
In this section, you’ll want to include three to five years of income statements, cash flow statements and balance sheets.
It can also be helpful to include:
An expense analysis.
A break-even analysis.
Capital expenditure budgets.
Projected income statements.
Projected cash flow statements.
If you have collateral that you could use to secure a loan, you should list it in this section as well.
If you’re a startup that doesn’t have much historical data to provide, you’ll want to include estimated costs, revenue and any other future projections you may have. Graphs and charts can be useful visual aids here.
Appendix
Finally, if necessary, supporting information and documents can be added in an appendix section. This may include:
Credit histories.
Resumes.
Letters of reference.
Product pictures.
Licenses.
Permits.
Contracts.
Any other relevant legal documents.
What lenders look for in a business plan
Lenders will typically evaluate your loan application based on the five C’s — or characteristics — of credit: character, capacity, capital, conditions and collateral.
Although your business plan won't contain everything a lender needs to complete its assessment, it can highlight your strengths in each of these areas.
Character
Lenders assess your character by reviewing your education, business experience and credit history. They may also check the backgrounds of your board members and management team. You can highlight your character strengths in the following sections of your business plan:
Executive summary.
Company overview.
Management team.
Capacity
Capacity refers to your ability to repay the loan. Lenders look at the revenue you plan to generate, your expenses, cash flow and your proposed loan payment plan. You can cover this in the following sections:
Funding request.
Financial statements.
Capital
Capital is the amount of money you’ve invested in your business. Lenders can use it to gauge your financial commitment to the business, which you can highlight in any of the following sections:
Operational plan.
Funding request.
Financial statements.
Conditions
Conditions refers to the purpose and market for your products and services. Lenders look for information such as product demand, competition and industry trends, which you can cover in:
Market analysis.
Products and services.
Marketing and sales plan.
Collateral
Collateral is an asset pledged to a lender to guarantee the repayment of a loan. This can be equipment, inventory, vehicles or something else of value. Include this information in:
Operational plan.
Financial statements.
Appendix.
» MORE: How to get a business loan
Business plan examples
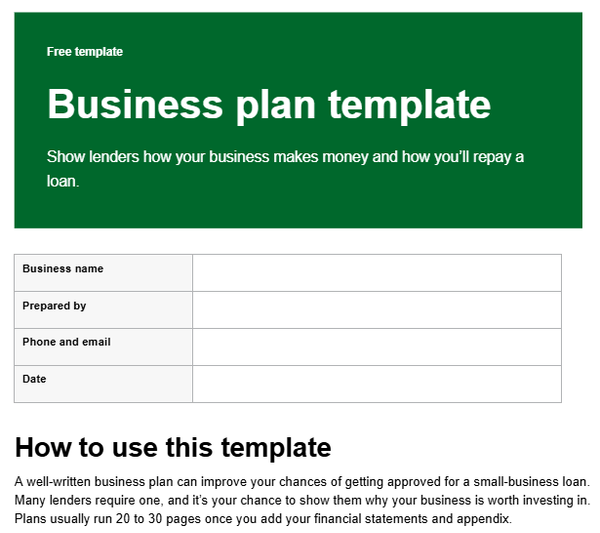
Writing a business plan for a loan application can be intimidating, especially when you’re just getting started. It may be helpful to use a business plan template or look at existing samples as you go through the draft process.
You can use NerdWallet’s free business plan template to help get you started.
Resources for writing a business plan
SCORE. SCORE, a nonprofit organization and resource partner of the U.S. Small Business Administration, offers free assistance that includes a step-by-step downloadable template to help startups create a business plan, and mentors who can review and refine your plan virtually or in person.
Small Business Development Centers. Similarly, your local SBDC can provide assistance with business planning and finding access to capital. These organizations also have virtual and in-person training courses, as well as opportunities to consult with business experts.
Business plan software. Although many business plan software platforms require a subscription, these tools can be useful if you want a templated approach that can break the process down for you step-by-step. Many of these services include a range of examples and templates, instruction videos and guides, and financial dashboards, among other features. You may also be able to leverage AI tools to get you started. Just make sure you’re specific with your original prompt and give it enough context for an effective outline.
Frequently Asked Questions
What is a business plan for a loan?
A loan business plan outlines your business’s objectives, products or services, funding needs and finances. The goal of this document is to convince lenders that they should approve you for a business loan.
Do you need a business plan to get a loan?
Not all lenders require a business plan, but you’ll likely need one for bank and SBA loans. Even if it isn’t required, however, a business plan can bolster your loan application.
Why do lenders ask for a business plan?
Lenders ask for a business plan because they want to know that your business is and will continue to be financially stable. They want to know how you make money, spend money and plan to achieve your financial goals. All of this information allows them to assess whether you’ll be able to repay a loan and decide if they should approve your application.