


You’ve probably heard of getting ghosted by a romantic interest. One minute, they’re love bombing you. The next … crickets.
It turns out that many people act the same way toward their finances. Thinking about money is so stressful or overwhelming that they turn away from it, leaving statements unchecked and apps unopened for long periods of time.
“It’s easy to get caught up in a negative feedback loop where you know you’re under stress about your bills. You walk away to make it feel better,” says Steven Conners, founder and president of Conners Wealth Management in Scottsdale, Arizona.
The problem with financially ghosting yourself is that it’s easy to overspend, run up debt or create other financial problems when you’re not paying attention.
Here’s how to quit ghosting your finances and get back on track.
Log in and look around
If you’ve been avoiding taking a look at your bank, credit card and other financial accounts, set aside time to dig in.
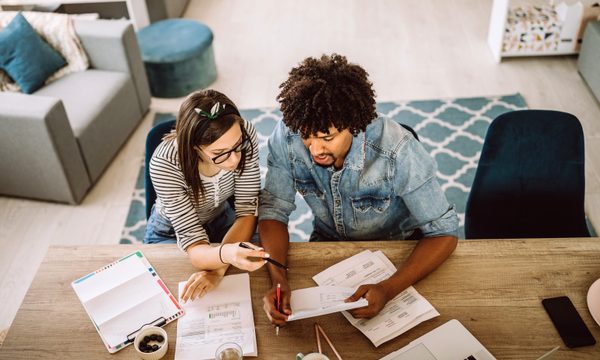
Wanda Belle, an accredited financial counselor and founder of Belle Financial Services in the Atlanta area, suggests printing out statements when possible so it’s easier to comb through them.
“Highlight any expenses that surprise you,” she says. Belle encourages people to avoid judgment or shame. Focus on bringing awareness to the numbers.
Set some achievable goals
Once you’ve reviewed spending from the last month or two, Belle suggests giving yourself a new goal for the coming months. Perhaps you want to decrease restaurant spending by $100, or keep online shopping expenditures under a certain limit.
“Focus on variable expenses because you have more control over them,” she says.
Those are the expenses that fluctuate each month like groceries, rideshares or eating out, and they’re easier to cut back than fixed expenses like rent or car payments.
Meet MoneyNerd, your shortcut to smart money moves
NerdWallet's twice-weekly newsletter offers practical, no-fluff guidance to help you spend smarter, save more, and make confident money decisions. Delivered free to your inbox.
Take a look at the big picture
In addition to your spending, it’s helpful to dig into your overall money picture, including any loans, investments and other financial accounts.
That’s what Jason Bernat, president and CEO of American Financial Services, a wealth management company in Boardman, Ohio, does with clients when they’ve been ignoring their accounts.
“We go over all the bills, loans and assets, and identify what causes the most stress,” he says. “Then we can work backward to decide where to start.”
That first step could be as simple as opening up a new retirement account or increasing contributions to an existing one.
It could also be identifying a lingering balance you know you need to pay off.
Dial down debt and ramp up savings
Since debt can be a major money stressor, Bernat suggests prioritizing paying down credit card debt with any savings generated from your spending shifts.
“Paying down debt will make everything else more manageable,” he says.
At the same time, you also want to save what you can. Building up an emergency savings fund can protect you from having to take on more debt in the event of an unexpected expense, like a car repair or medical bill.
Both paying down debt and building up an emergency fund can take time, Bernat says.
“Don’t try to fix everything in a weekend. Pick one financial issue that’s creating the most stress at a time.”
Calm your nervous system
If you’re resisting money management tasks because of the stress you associate with the experience, Conners suggests pairing your financial work with a physical activity.
“I’ve learned that it’s easier to manage your emotions when you have a coping mechanism like working out, going to the gym or going for a long walk. You get the tension and anxiety out of your system,” he says.
In that calmer state, it’s easier to tackle difficult tasks, Conners says. If exercise isn’t your thing, then another calming activity like watching movies, listening to music or knitting could work.
Put on your favorite jazz playlist while you pay bills, log in to your banking app while out on a walk, or grab your favorite beverage before making a budget.
Track your progress
With your fear of financial intimacy hopefully dissipating, you can keep a closer eye on your cash flow.
Document your spending and check in throughout the month to stay on track with your new goals, Belle says. After a month, review your new statement.
If you met your goals, pick a new category to focus on next month. If you didn’t, commit to making other adjustments and try again.
“Either way, you’re more aware of where your money is going and more intentional about future purchases,” she says.
In other words, you’re controlling your finances instead of ghosting them.