




Most budgets are built around your expenses. But the pay yourself first method, sometimes called "reverse budgeting," flips that approach on its head by prioritizing savings goals before paying your bills.
That doesn’t mean you skip or deprioritize your housing, utilities, transportation and grocery bills. It just means they’re budgeted for after you put money toward your savings goals.
This budgeting method is the opposite of what many people do: pay bills first, then put money aside for savings goals with what’s left. In this case, you’re saving a set amount first and then using the rest to cover your needs and wants.
🎯 Pay yourself first budgeting is good for people with a stable, predictable income and might be less effective for those with variable income, like freelancers, gig workers or those who make commission-based incomes.
How pay yourself first budgeting works
Step 1: Assess your spending
To make this budget successful, you’ll have to prepare. That starts with figuring out how much you spend each month.
Pull up your bank and credit card statements to see where your money goes. If you use a budgeting app, log in and get the details.
“Do the math and start conservative,” says Rachel Podnos O’Leary. “You can always increase (your savings contributions) later. You don’t want to risk an overdraft or bounced check or something like that.”
» MORE: The best budget apps right now
Meet MoneyNerd, your weekly news decoder
So much news. So little time. NerdWallet's new weekly newsletter makes sense of the headlines that affect your wallet.
Step 2: Identify your savings goals
It's impossible to know how much to save if you don't outline your savings goals first. Start by listing your short-term and long-term savings goals.
Saving for retirement and building an emergency fund that covers three to six months of living expenses should be your first priorities.
You can put a little money toward each savings goal or choose a couple to focus on first. Figure out how much you can afford to save each month based on your priorities.
Keep in mind: Other savings goals, like saving for a vacation, wedding or purchasing holiday gifts should come out of your “wants.”
Step 3: Determine how much to pay yourself
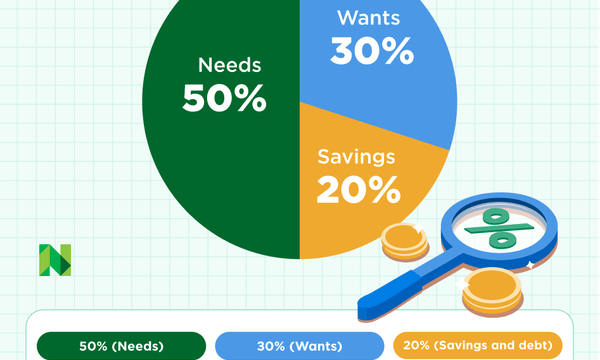
Decide what percentage of your income to save before paying for anything else. A common starting split — similar to the 50/30/20 budget — looks like this:
- 20% to savings (pay this first)
- 50% to needs (housing, utilities, groceries, transportation)
- 30% to wants (dining out, streaming services, gym membership, shopping)
There’s one exception: If you’re carrying high-interest debt, such as a credit card balance, pay that down after you’ve captured any 401(k) employer match and set aside a starter emergency fund.x Interest costs on that debt will likely outpace what you’d earn in savings.
The percentages aren't fixed, so you can adjust them as needed to fit your life. For example, you might save more and spend less on wants if you want to reach your goals faster, like building an emergency fund or boosting your investment portfolio.
Step 4: Adjust as needed
Ideally, your income should cover your needs, wants and savings goals with room to spare. But if money feels tight, there are ways to adjust:
- Focus on one savings goal at a time
- Cut back on spending in your "wants" category
Putting the numbers to work: An example
Say you bring home $3,400 a month. Using the 20/50/30 split — 20% to savings, 50% to needs, 30% to wants — your paycheck would break down like this:
- Savings (20%): $680
- Needs (50%): $1,700
- Wants (30%): $1,020
That $680 in savings isn't just one lump sum — it's worth splitting across your specific goals.
For example, you might put $200 toward an emergency fund and $250 toward retirement. That's $450 accounted for, which means you've already paid yourself first before touching another dollar. The remaining $230 could go toward extra payments on high-interest debt, like a credit card balance.
Once savings and debt paydown are set aside, the rest of your income — $2,720 — is left to cover your needs and wants, split however fits your life.
Pros and cons of paying yourself first
Pros
Low maintenance compared with other methods like zero-based budgeting (where you have to track every expense).
Helps you focus on big-picture goals and avoid impulse spending.
Easy to automate. Use payroll deductions for retirement accounts and set up automatic transfers to high-yield savings accounts or IRAs.
Cons
May not be the best choice if you have high-interest debt.
Savings could take priority over more urgent financial needs, like paying down debt.
Paying yourself first could leave you short on bills if you don’t plan carefully.
Ready, set, save
Paying yourself first is a great option if you prefer a hands-off budgeting system or don't want to feel as though you’re budgeting at all. Automate your savings for an easier experience.
If you need more structure, consider a more involved budgeting method:
- Envelope system portions out your entire income in cash toward all of your expenses at once using individual envelopes labeled for every item in your budget.
- Zero-based budgeting gives every dollar a job, such as paying bills, saving or spending, until there's nothing left unassigned.
The best budgeting system isn't the most popular one — it's the one you'll actually stick with.
Meet MoneyNerd, your weekly news decoder
So much news. So little time. NerdWallet's new weekly newsletter makes sense of the headlines that affect your wallet.