


How to Buy Homeowners Insurance
Here’s how to find the right home insurance for your needs.

Here’s how to find the right home insurance for your needs.
If your house goes empty for more than a month or two, you might need special coverage.

Home insurance isn’t required by law, but it may be required by your mortgage lender.

If your homeowners insurance premium has skyrocketed, there are steps you can take.

Homeowners insurance discounts can help you save when premiums go up.

Home insurance may cover tree removal if the tree falls on your home for a reason covered by your policy, like a storm or lightning strike.

Condo insurance in the U.S. costs $510 per year, on average, a NerdWallet analysis found.

Homeowners insurance doesn't cover termite damage in most cases. Here’s how to prevent it from happening in the first place.

Climate change brings greater risk — and more expensive home insurance.

Equipment breakdown insurance can save you money if a household appliance is damaged due to a mechanical or electrical issue.


Medical payments coverage for home insurance can cover medical expenses, regardless of fault.

Actual cash value coverage may lower your premiums, but it could also leave you underinsured.

One pays the current value, minus depreciation; the other pays the full cost to replace your property.
Even Floridians who don’t live near the beach may want to consider buying flood insurance.
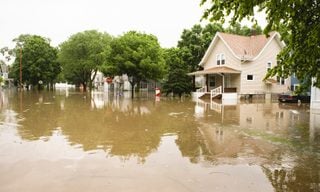
Even if you’re not required to buy flood insurance, your home could still be at risk.

Homeowners insurance generally covers damage from sudden, accidental plumbing problems.

A homeowners insurance deductible is the part of a claim you’ll pay out of pocket.

This coverage could help pay for unexpected costs after a claim.

A homeowners declarations page lists coverage limits, your policy’s cost, the expiration date and other key info.
The average cost of flood insurance in the U.S. is about $976 per year, or $81 per month.