


Many popular credit cards from well-known issuers offer valuable benefits and rewards. But there are some lesser-known cards — whether they're from smaller banks or credit unions, or simply just less-heralded products from bigger players — that come with rare but impressive perks that few other cards offer.
The following cards feature some hard-to-find benefits, like higher-than-usual rewards rates, uncommon rewards categories or seriously valuable side perks.
1. Robinhood Gold Card
It's likely you've heard of the Robinhood investing platform, and perhaps you're also aware that it offers a co-branded credit card or two. But the Robinhood Gold Card remains elusive to many (more on that below). Still — if you can get it — it offers a market-leading and uncapped 3% cash back on all purchases, plus 5% back on travel booked through Robinhood’s travel portal. Redemption options are varied and include a deposit into a Robinhood brokerage account, statement credit, gift cards and travel booked in Robinhood’s portal.
Drawbacks
To qualify for the card, you must have a Robinhood Gold membership, which costs either $50 annually or $5 monthly. Also, while the card debuted in March 2024, it's still not widely available to the public. You must join a waitlist to "reserve" a spot for a chance to apply.
2. Nibbles credit card
There aren't a lot of pet-centered credit cards on the market to begin with, so the Nibbles credit card is already somewhat rare by nature. But what makes it truly unique, and valuable, is its pet insurance benefit. The card offers up to $25,000 in yearly health coverage for accidental injury and illness for one pet, which can be used at any licensed vet across the U.S. The card’s insurance offers 80% coverage and a maximum deductible of $950. Holders also earn 3% cash back on eligible pet-related expenses — an unusual bonus category that includes food but also biggies like vet bills, boarding and sitting — plus 1% cash back on all other spending. The card doesn't charge an annual fee.
Drawbacks
As of this writing, there are limitations to the card’s pet insurance eligibility process. For example, older pets with established conditions will most likely not be approved. If your pet doesn’t qualify for coverage, you can still get the card, but you’d be losing out on its most valuable feature.
3. Aven Home Equity Visa Credit Card
Traditional secured credit cards use cash deposits as collateral, typically no more than $1,000. The amount you put down for a security deposit becomes your credit limit. While the Aven Home Equity card is a secured card, it offers the possibility of much higher credit lines, ideal for those looking for more spending power. That's because rather than being secured by cash, Aven Home Equity cards are backed by the equity in your home. Aven says that credit limits max out at $400,000.
The card also earns an unlimited 2% cash back on all purchases.
Drawbacks
Yes, the Aven card has plenty of appeal, but its benefits should be weighed against its primary drawback. Because home equity is the collateral backing your credit card, you could lose your home if you don’t pay your credit card balance.
🤓Nerdy Tip
Another asset-secured card, the Yendo credit card, is backed by the value of your car. It offers credit limits up to $10,000, and it earns an unlimited 1.5% cash back on all purchases. Be aware, though, that defaulting on your credit card payments could result in the repossession of your car. 4. Venmo Credit Card
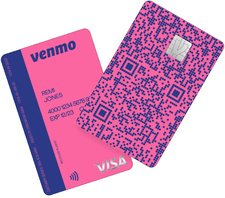
Typically, credit cards that offer bonus rewards for “groceries” or “supermarkets” flatly exclude wholesale/warehouse clubs from those categories. The Venmo Credit Card, however, is one of the few that specifically includes "wholesale clubs" as a possible 3% "grocery" bonus category. The card also stands out for its unique QR code on the front of the card that others can scan with their phones, making it easy to split costs among people. You’d be hard-pressed to find a similar card with those two distinctive features.
Drawbacks
Despite some features that make the card easy to use, the Venmo Credit Card’s rewards structure is not straightforward. While you don't have to manually "activate" or "opt in" to bonus categories, you do still have to remember what they are and which ones you plan to focus your spending on to earn bonus rates. Plus, you must use the card with the Venmo app, so if you’re not already a Venmo customer and don't care to be, the card won’t make sense for you.
» MORE: What is Venmo?
5. Bilt Obsidian Card
The $95-annual-fee Bilt Obsidian Card — issued by little-known Column N.A. Bank — makes this list because it allows cardholders to earn rewards on housing payments and avoid processing fees while doing so. The card offers two ways to do this, and cardholders must select one option:
- Housing-only option: You can earn up to 1.25x Bilt Points on rent or mortgage payments with no transaction fee. Your rate will depend on how much non-housing spending you put on the card. (To earn the top 1.25x rate on housing payments, you need to spend at least the same as your housing payment on other non-housing purchases in that month.)
- Bilt Cash option: With this option, you can earn 1x Bilt Point on housing payments. But to do so, you'll need to have amassed enough Bilt Cash — a secondary rewards currency — to "unlock" those points. (For every $30 in Bilt Cash you spend for this purpose, you’ll earn 1,000 Bilt Points on your rent or mortgage payment.) Up to $100 of Bilt Cash earned rolls over to the next year.
Bilt offers two additional cards — the $0-annual-fee Bilt Blue Card and the $495-annual-fee Bilt Palladium Card — both of which can also earn rewards on housing payments. But if that's really the main feature you're interested in, the Bilt Obsidian Card may represent the best midrange combo for many people: solid rewards for a reasonable annual fee, without too many extras to track.
Drawbacks
The Bilt Obsidian Card — like all the Bilt cards — can be a hassle to carry and is decidedly not low-maintenance. As you can tell from above, its complex rewards structure requires closely tracking your spending in order to maximize your housing rewards.
6. Atmos™ Rewards Summit Visa Infinite® credit card
The $395-annual-fee Atmos™ Rewards Summit Visa Infinite® credit card — the newer of two co-branded cards for both Alaska and Hawaiian airlines — offers multiple innovative features that help set it apart from other airline cards. For starters? Each year cardholders automatically get one Global Companion Award of 25,000 points, which is applied as a discount to the total points price of a flight and can be redeemed for any service class on any flight in Alaska’s network, including flights with Hawaiian Airlines and eligible international partners. It's even possible to earn a second one — this time an award of 100,000 points — by spending $60,000 on the card in an anniversary year.
The card also offers a rare and valuable bonus category: "foreign purchases.” This includes purchases made in a foreign currency and transactions made or processed outside of the United States and its territories made in U.S. dollars. No other co-branded credit card from a major U.S. airline offers such a category.
Additionally, cardholders get a hassle-free automatic $50 travel delay credit for flight cancellations or departure delays of more than two hours. Other airline cards with similar benefits typically have far more complicated restrictions.
Drawbacks
Although the card’s perks can make up for its annual fee, a $395 yearly price tag is steep and can be restrictive for some. Also, if you’re not a frequent Alaska (or Hawaiian) flyer, it will be more difficult — though not impossible — to extract the most value from it.
» LEARN: How to redeem Alaska Airlines miles
Other cards with unique features
Many of the following cards are from major issuers and hence aren't obscure products, but they do offer uncommon perks.
- Bank of America® Customized Cash Rewards credit card: Holders of this card can earn bonus cash back in a category of their choice, which includes the relatively rare home improvement category. (Terms apply.) Everything from hardware stores to roof contractors to air conditioning repair services qualify to earn the elevated rate.
- B&H Payboo Credit Card: Issued by Comenity Capital Bank, this card is unique because it offers rewards in the form of a sales tax rebate. (Holders also have the option of choosing a special financing offer with the card, instead of the rebate.) Note that you can only use the card at B&H, the New York City-based photography, video and audio equipment store.
- Secured Chime Visa® Credit Card: Among so-called alternative credit cards for those with bad or no credit, this $0-annual-fee card is a stellar option. It doesn't require a credit check, doesn’t require a minimum security deposit, nor does it charge an APR. The card also earns rewards if you meet certain criteria, and it reports to all three major U.S. credit bureaus. That’s a rare combination of perks in a card designed to help you build credit.
- GBank Visa Signature credit card: Apt for gamers and betters, this card earns an unlimited 1% cash back on transactions in gaming and sports app loads — an uncommon credit card rewards category. The card also earns an unlimited 2% cash back on all other purchases.
- Karat credit card: A super niche product, the Karat card is designed for content creators. As such, your credit limit is partly determined by the size of your following, and you can customize your Karat card with your logo. Redemption options are similarly tailored to the target audience and include camera equipment, ad spend and a Times Square billboard.
- State Farm® Premier Cash Rewards Visa Signature® Card: This option earns bonus cash back on common household expenses like grocery stores and dining, but what makes it stand out is that it also gets you 3% cash back on insurance premium payments, on up to $4,000 spent annually. That's an unusual bonus category that could make sense for those who carry multiple policies. Note that you have to be a State Farm customer to be eligible for the card.
- United Gateway℠ Card: A free checked bag benefit is common among high-end travel cards — but it’s rare to find that sought-after perk in a $0-annual-fee airline card. With United Gateway℠ Card, you can get two complimentary checked bags per year on United or United Express flights after spending $10,000 per year on the card.
- U.S. Bank Smartly™ Visa Signature® Card: Holders of this card earn an unlimited 2% cash back on all purchases — which already puts it on par with the best flat-rate cash-back cards. But what lands the card on this list is that its 2% base rate can jump to 2.5%, 3% and even 4% back — on all purchases — for cardholders who meet certain balance requirements. (You'll only earn this elevated rate on $10,000 in spending per billing cycle.) You’ll need at least $10,000 across eligible personal U.S. Bank accounts to boost your earnings rate to 2.5%, $50,000 to earn the 3% rate and $100,000 to get the outstanding 4% back. Also, you must have a U.S. Bank account to get the full value of the base 2% cash-back rate.