

Key takeaways
- SBA Form 413, also called the Personal Financial Statement, is part of the application process for most SBA loans.
- The form lists your personal assets and liabilities, which helps the lender and the SBA determine your ability to repay the loan.
- Information you enter on the form must be current within 90 days of submitting the form for a disaster loan. For 7(a) and 504 loans as well as 8(a) and WOSB programs, information must be up to date within 120 days of submission.
- Owners with 20%+ equity must include the assets and liabilities of their spouse and any minor children.
- A low net worth alone typically won't disqualify you. The SBA and lenders also weigh your credit history, debt types and business cash flow.
What is SBA Form 413?
SBA Form 413, formally titled “Personal Financial Statement,” is a document that the U.S. Small Business Administration uses to assess the creditworthiness and repayment ability of its loan applicants. This form collects information about your personal finances, such as assets, liabilities and sources of income.
You’ll be required to complete SBA Form 413, or your lender’s equivalent, as part of the application for most SBA loans.
The SBA also uses this form to determine whether a business meets the qualifying criteria for some of its contracting programs.
How much do you need?
We'll start with a brief questionnaire to better understand the unique needs of your business. Once we uncover your personalized matches, our team will consult you on the process moving forward.
Who needs to fill out SBA Form 413?
If you’re applying for any of the following SBA loans or programs, you’ll almost certainly need to complete Form 413:
- Women-Owned Small Business (WOSB) Federal Contracting Program.
SBA microloans are administered by intermediary partners, which set their own application requirements. While a microlender may not require SBA Form 413, it will most likely ask for a personal financial statement in some format.
SBA Form 413 must be completed by the following business applicants:
- Each proprietor.
- Every general partner.
- Every managing member of an LLC.
- Each owner with 20% or more equity in the business.
- Any person or entity providing a guarantee on the loan.
If you own 20% or more of the business and are married, the SBA requires you to include your spouse's assets and any minor children's assets on the form. This information is required so that the SBA knows that you have joint assets or liabilities.
Underwriting in the real world
The requirement to include a spouse's finances applies regardless of where you live. But it tends to trip up applicants, especially in community property states — Idaho, Louisiana, New Mexico, Nevada, Arizona, California, Texas, Washington and Wisconsin — where a spouse's debts are more likely to be treated as jointly owed.
Amber Young, vice president, SBA loan processing manager at Beneficial State Bank, put it like this: "I think a lot of people don't realize that they're living in a community property state ... even though there is an area for the spouse to sign, they don't necessarily realize that it's a requirement for us to look at those assets and debt."
Ownership situations that surprise applicants
The specifics of the 20% owner threshold get a bit complex. Here are a few common scenarios that could catch you off guard if you’re not prepared for them:
- Spousal and minor-child ownership is combined. That means if you own a percentage of the business and your spouse and/or minor child does as well, and the combined ownership percentage is 20% or more, then you’ll be completing Form 413.
- Indirect ownership counts. Even as an indirect owner, if you have 20%+ stake in the business, you’ll be filling out Form 413.
- Reducing ownership stake before applying doesn’t necessarily exempt you. Lowering your ownership stake shortly before you apply doesn't necessarily get you out of the personal financial disclosure requirements.
Your lender may also ask you to file even if you don’t fall into any of the above categories.
How to fill out SBA Form 413
Follow these steps to complete SBA Form 413.
Step 1: Gather financial documents
SBA Form 413 requires a breadth of information. The SBA estimates that the form should take around 90 minutes to complete. Total time to complete will vary, of course, depending on the circumstances of your business and how organized your financial documents are. Getting organized before you start filling out the form will help move the process along.
You may not need to provide these documents to your SBA lender, but they can be useful for completing the form more quickly and accurately:
- Bank statements.
- Retirement account statements (e.g., IRA, 401(k) accounts).
- Life insurance documents.
- Documents concerning any personal investments, such as stocks and bonds.
- Pay stubs showing your annual salary.
- Statements showing any additional forms of income.
- Mortgage statements, auto loan statements, credit card statements and documentation of any other personal debt.
You should ensure that your financial documents are current — within 120 days of your application submission. If you’re filling out an application for an SBA disaster loan, your information should be up to date within 90 days of submission.
Keep in mind that you can reach out to your lender, business accountant or local Small Business Development Center if you need assistance completing Form 413.
🤓Nerdy Tip
If you’re self-employed, we, and three SBA preferred lenders we consulted, highly recommend separating your personal and business finances. That’s bank accounts as well as credit cards. Scrambled finances are one of the top issues that lenders see with self-employed SBA loan applicants. And this form is one of the first places that will become an issue with your application.Step 2: Select your loan or contracting program
On the first page of Form 413, check the box that corresponds to your application: SBA 7(a) loan; SBA 504 loan or surety bond; disaster loan; Women-Owned Small Business (WOSB) program or 8(a) program.
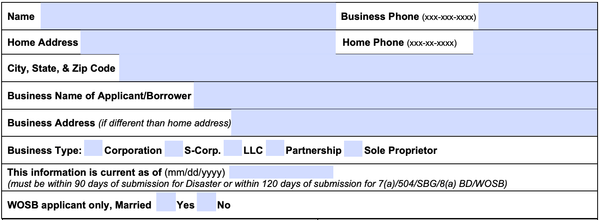
Step 3: Fill in personal and business information
Enter your name, home address and home phone number, as well as your business name, address and phone number.
Select your business entity type and enter the date as of which your information is current. If you’re applying for the WOSB Federal Contracting Program, indicate whether you’re married.
Download SBA Form 413
Download Form 413 via the SBA website. You may also be able to get the form from your individual SBA lender.
Step 4: Add your assets and calculate their total value
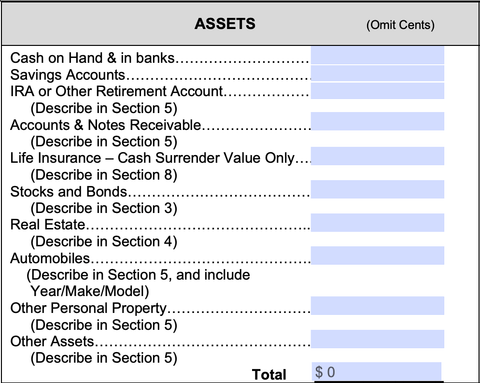
When filling in this section, you’ll need to include accurate information for both your and your spouse’s assets. The form specifies that you should “omit cents.” So, round your valuations to the nearest dollar amount. Avoid loose estimates here, however, and be prepared to support any figure a lender asks about.
Here’s what you’ll need to include:
- Cash on hand and in banks. Along with cash, the amount in your and your spouse’s checking accounts.
- Savings accounts. Include the amount in any money market and CD accounts as well.
- Other assets. Estimate the value of any other assets you own that don’t fall into the above categories. You'll also describe this in detail in section 5.
- Retirement accounts. The value of your IRA or any other retirement accounts in your name, as well as your spouse’s name (if applicable).
- Accounts and notes receivable. You’ll only need to fill this out if you’ve personally loaned money and that amount is still owed to you.
- Life insurance — cash surrender value only. If your life insurance has a cash payout, list the dollar amount you would receive if you canceled it. This only applies to whole life insurance policies, not term life insurance. You'll describe this in detail in section 8.
- Stocks and bonds. List the current value of all stocks and bonds owned by you and your spouse.
- Real estate. List the current fair market value of all real estate you and your spouse own. You’ll describe this in detail in section 4.
- Automobile. The current fair market value of all cars or other automobiles you and your spouse own (not the automobiles you’re leasing).
- Other personal property. Estimate the combined worth of all the valuable material items you own and could sell for cash but that don’t fall into any of the above categories (e.g., jewelry, electronics and antiques). You'll describe this further in section 5.
🤓Nerdy Tip
Don’t be surprised if your lender questions the value you enter for your residence. The resources available to you to enter this value, often a site like Zillow or similar, may not get it quite right. And if your residence is listed as collateral, the lender will likely do its own appraisal or internal valuation, Amber Young, vice president, SBA loan processing manager at Beneficial State Bank, tells us.Once you’ve entered all of your information, you’ll add up the column to calculate the total value of your assets.
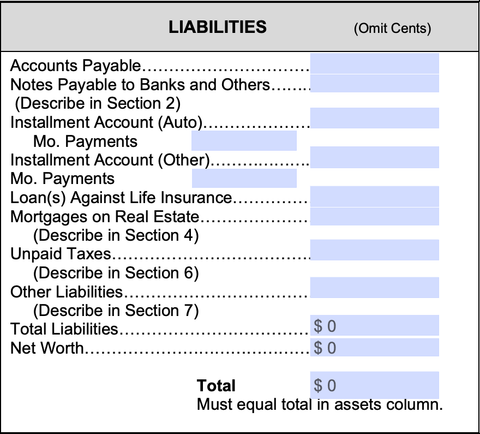
Step 5: Add your liabilities and calculate their total value
In this section of Form 413, you’ll want to include your liabilities as an individual — and if you’re married, any liabilities you hold jointly with your spouse — just like the assets section.
Here’s what you’ll need to include:
- Accounts payable. This field refers to any debts you owe to a third party (other than banks) usually on a short-term basis (i.e., 30, 60 or 90 days). Most applicants can leave this section blank.
- Notes payable to banks and others. This is where you’ll list all outstanding balances on your personal credit cards or lines of credit. You'll describe this information further in section 2.
- Automobile installment account. Provide the total balance and monthly payment amount for any outstanding automobile loans.
- Other installment accounts. List the total and monthly payment amount of any outstanding personal installment loans on your books, including student and personal loans.
- Loan against life insurance. Provide the balance of any loans you’ve taken out for which you’ve pledged your life insurance policy as collateral (only if it was whole life insurance).
- Mortgages on real estate. The balance of mortgages on your owned real estate. You'll describe this in detail in section 4.
- Unpaid taxes. List any taxes that are currently due but unpaid. You'll describe this further in section 6.
- Other liabilities. Provide the total amount of any other outstanding debt not listed in the previous sections. Most applicants don’t have any additional liabilities; but if you do, you can describe them in detail in section 7.
After completing all these details, you’ll add up the numbers in the column to get your total liabilities. Next, you’ll calculate your net worth by subtracting your total liabilities from your total assets.
If your liabilities are greater than your assets — and you don’t have a high net worth — it doesn’t mean you won’t be able to qualify for an SBA loan. The SBA wants to understand your current debts and will use this information, in addition to the rest of your application, to evaluate your repayment ability.
Step 6: Fill in your sources of income and contingent liabilities
Section 1 of SBA Form 413 requires you to fill in your sources of income, including:
- Salary. Provide your and your spouse’s total annual salaries (if applicable), as reported on your tax return.
- Net investment income. List any income you earn as dividends and interest from your investments.
- Real estate income. Provide the net income (i.e., income you earn after expenses) you receive from any of your owned real estate properties through leasing or renting them out.
- Other income. Provide the total amount of any income received through avenues not listed above.
If you have other income, such as a pension or social security, you’ll elaborate on that income in the “description of other income” box. You don't have to disclose alimony or child support income unless you want it considered in evaluating your application.
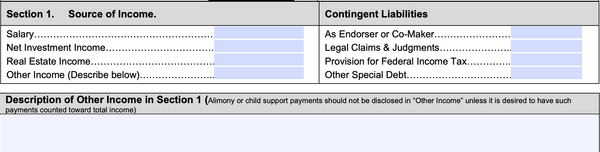
In the contingent liabilities box, you’ll add the debts you’re responsible for if certain conditions take place, including:
- As endorser or co-maker. Outstanding debts for which you or your spouse acted as guarantor or co-signer.
- Legal claims and judgments. The total amount you might owe for any pending legal claims or judgments.
- Provision for federal income tax. The amount of money you’re setting aside to pay federal taxes that have accrued but aren’t yet due.
- Other special debt. The total amount of any other outstanding contingent debts not listed above.
Depending on your individual financial situation, you may not have anything to complete in this part of the form. If you do, remember that contingent liabilities are not included as part of the liabilities total used to calculate net worth.
Step 7: Provide additional details regarding assets and liabilities
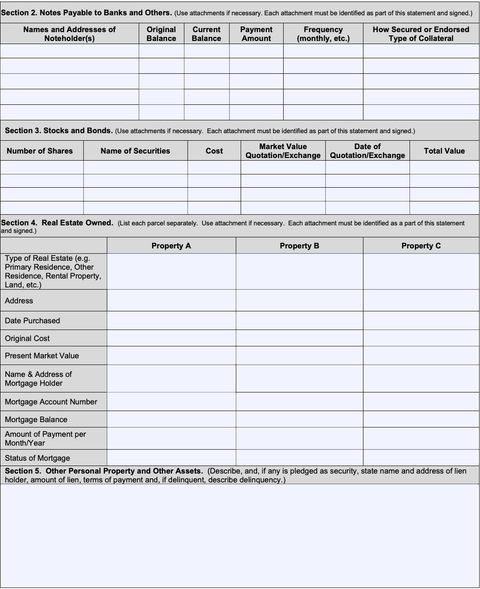
After completing section 1, you’ll continue the form by filling out sections 2 through 8. Each of these sections will ask you to provide additional information regarding the assets and liabilities you listed earlier.
Depending on your finances, you may not need to complete all of these sections, or provide extensive details.
- Section 2. Fill in details regarding your notes payable to banks and others, such as credit card accounts.
- Section 3. Add information explaining your stocks and bonds.
- Section 4. Provide details regarding any real estate you own.
- Section 5. Describe anything you included as other personal property or other assets.
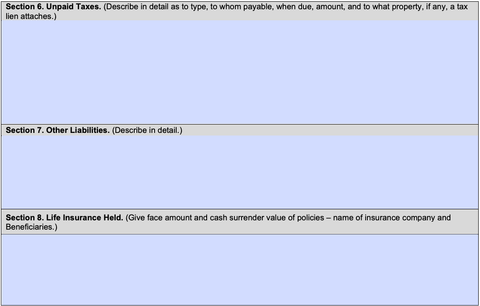
- Section 6. Detail any information regarding your unpaid taxes.
- Section 7. Describe anything you included as other liabilities.
- Section 8. Add information regarding any life insurance policies you accounted for in the assets box.
For Sections 2 through 4, if you need to include attachments, each one must be identified as part of your SBA personal financial statement and signed.
Step 8: Review the form
SBA Form 413 is nearly finished once you’ve completed sections 1 through 8. Before you sign and date, however, you should thoroughly review the information you’ve provided.
Consider asking a business accountant, attorney or loan specialist to review your document as well, so that you can avoid mistakes that may impact your application.
Filling out Form 413 completely and correctly will help expedite the underwriting process for your SBA loan.
Step 9: Sign and date
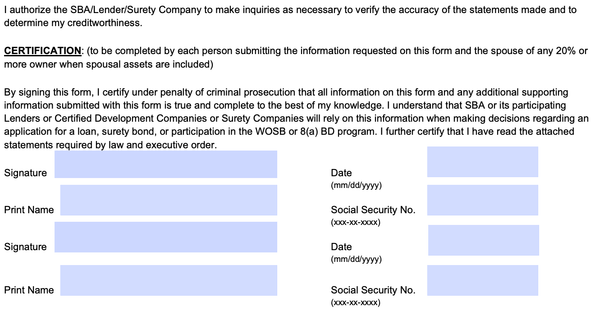
Once you’re satisfied that you’ve completed your personal financial statement accurately, you’ll need to sign and date the document. You, the borrower, will sign and date the form, as well as provide your Social Security number.
If you’ve included your spouse’s assets and liabilities on the statement, your spouse must also sign the form. This is true regardless of whether your spouse is a guarantor or has any stake in the business.
Learn more about getting an SBA loan:
- Follow these five steps to apply for an SBA loan.
- Compare current SBA loan rates.
- Find out how long it takes to get an SBA loan.
Frequently Asked Questions
Do I need a CPA to prepare SBA Form 413?
No, you as the owner complete and sign SBA Form 413, though you could certainly consult a CPA if your business finances are particularly complex. Otherwise, the form should be straightforward enough to complete on your own, particularly if you’ve been diligent about separating your personal and business finances.
What if a line of SBA Form 413 doesn't apply to me?
Leaving fields blank may give the impression you’ve missed certain parts of the form. If a line doesn’t apply to you, enter $0 or N/A as appropriate.
Does my spouse have to sign if they don't own any of the business?
Yes, if you and your spouse have joint assets and/or liabilities, you will record those on SBA Form 413. Your spouse must then sign the form, even if they don’t own any of the business.
What happens if my Form 413 goes stale during underwriting?
This is a reality that applicants often encounter. If your form is no longer within the required currency timeframe during underwriting, you’ll be asked to update the form. This, of course, delays the underwriting and funding timeline. However, many lenders hedge for this by giving you a tighter internal window. It’s important to remember here that the clock starts running from the date you submit, not the date you sign the form.