

Mortgage rates are starting off this week with a nice drop, though the likely reason for the fall could be a little anxiety-inducing.
The average interest rate on a 30-year, fixed-rate mortgage dropped to 7.20% APR, according to rates provided to NerdWallet by Zillow. This is 15 basis points lower than Friday and 12 basis points lower than a week ago. (See our chart below for more specifics.) A basis point is one one-hundredth of a percentage point.
Rates started this slide last week, as investors' previously sky-high confidence in AI came a little closer to earth. Tech stocks lost a bit of their luster, and bonds looked more appealing. Greater demand for bonds pushed up bond prices, dropping bond yields (they move inversely). And mortgage rates are often indexed to the yield on the 10-year Treasury so, huzzah, lower mortgage rates.
On one hand, yay! But on the other hand … uh, what was that about stocks? For way more detail, keep reading below the chart.
Average mortgage rates, last 30 days
» Take the next step: Compare mortgage rates from NerdWallet’s top lenders
🤓 Kate on Rates, 10/15/26
📈 What influences mortgage rates?
Mortgage rates are constantly changing, since a major part of how rates are set depends on reactions to new inflation reports, job numbers, Fed meetings, global news ... you name it. For example, even tiny changes in the bond market can shift mortgage pricing.
Like I mentioned above, mortgage rates started edging lower last week as Treasury yields came down. Mortgage rates are generally benchmarked to the yield on 10-year Treasury notes, so where the yield goes, rates go, too.
The yield is basically the return investors get on a bond. A bond is a little piece of government or corporate debt; when an investor buys a bond, they're making a tiny loan to the issuer. The issuer agrees to pay them back a set amount over the bond's lifespan (that's the yield), and when the bond matures, the investor gets the bond's original price back. That's why unlike anything-could-happen stocks, bonds are generally considered relatively low risk.
A bond investor who buys a bond at issuance knows immediately: Here's my cost, here's what I'll earn and here's when my initial investment will be returned. When investors sell bonds to each other, things get more interesting, because the market now determines the price, and that shifts the relative value of the yield.
Here's how that works. If you bought a $100 bond with $5 annual yield payments, that yield is 5%. But say you want to sell that bond but can’t find a full-price buyer; the best price you can get for it is $80. The annual yield payments are still $5, but since they're relative to that lower price, the yield is now 6.25%.
For much of the summer and early fall, we saw lots of Treasury bond selling, which drove prices down and yields up. That kept pushing mortgage rates higher. Additionally, tech companies issuing loads of corporate bonds to help fund AI buildout meant that bond investors had a sexier option than Plain Jane Treasuries.
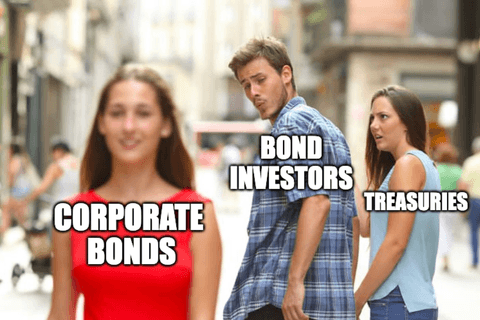
Last week, that dynamic reversed as doubts crept in about the potential profits from AI. September's Consumer Price Index, which came out last Wednesday, and Producer Price Index, from Thursday, showed that inflation's still running hot. If prices are climbing, the costs of building data structures and other AI infrastructure will increase, right? So to get solid returns on these investments, tech companies are going to have to make some serious profits. That right there is where some investors are having misgivings.
It sort of played out like a teen movie. Investors realized that the hot, popular girl (tech stocks) might not actually be all that, and their eyes turned to the reliable girl-next-door who'd been there for them all along (Treasuries).
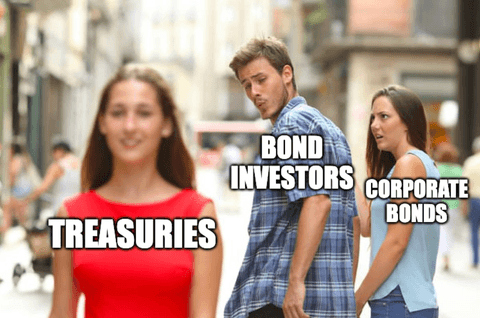
Just so we're clear: No one is saying the AI bubble is bursting, or really that there even is an AI bubble. But yes, prices for Treasuries went up and yields fell, so mortgage rates ebbed, too. Whether this downward trend will last depends on a lot of factors, including whether tech companies can convince investors that they're on track for strong profits and whether anything can improve fuel prices, since that's a massive factor in inflation.
» Learn more: How the Fed affects mortgage rates
Explore mortgages today and get started on your homeownership goals
Get personalized rates. Your lender matches are just a few questions away.🔁 Should I refinance?
Refinancing might make sense if today’s rates are at least 0.5 to 0.75 of a percentage point lower than your current rate (and if you plan to stay in your home long enough to break even on closing costs).
With rates where they are right now, you could start considering a refi if your current rate is around 7.70% or higher — but there just aren't too many people for whom that's true.
Also consider your goals: Are you trying to lower your monthly payment, shorten your loan term or turn home equity into cash? For example, you might be more comfortable with paying a higher rate for a cash-out refinance than you would for a rate-and-term refinance, so long as the overall costs are lower than if you kept your original mortgage and added a HELOC or home equity loan.
If you're looking for a lower rate, use NerdWallet's refinance calculator to estimate savings and understand how long it would take to break even on the costs of refinancing.
» Time to refi? Compare refinance rates from NerdWallet’s top lenders
🏡 Should I start shopping for a home?
There is no universal “right” time to start shopping — what matters is whether you can comfortably afford a mortgage now at today’s rates.
If the answer is yes, don’t get too hung up on whether you could be missing out on lower rates later; you can refinance down the road. Focus on getting preapproved, comparing lender offers, and understanding what monthly payment works for your budget.
NerdWallet’s affordability calculator can help you estimate your potential monthly payment. If a new home isn’t in the cards right now, there are still things you can do to strengthen your buyer profile. Take this time to pay down existing debts and build your down payment savings. Not only will this free up more cash flow for a future mortgage payment, it can also get you a better interest rate when you’re ready to buy.
» Is now a good time to buy? See NerdWallet’s analysis
🔒 Should I lock my rate?
If you already have a quote you’re happy with, you should consider locking your mortgage rate, especially if your lender offers a float-down option. A float-down lets you take advantage of a better rate if the market drops during your lock period.
Rate locks protect you from increases while your loan is processed, and with the market forever bouncing around, that peace of mind can be worth it.
🤓 Nerdy Reminder: Rates can change daily, and even hourly. If you’re happy with the deal you have, it’s okay to commit.
» Stay informed: Check out NerdWallet's mortgage news hub for all our latest coverage.
🧐 Why is the rate I saw online different from the quote I got?
The rate you see advertised is a sample rate — usually for a borrower with perfect credit, making a big down payment, and paying for mortgage points. That won't match every buyer's circumstances.
In addition to market factors outside of your control, your customized quote depends on your:
Credit score
Debt-to-income ratio
Employment history
Down payment
Type of mortgage
Location and property type
Loan amount
Even two people with similar credit scores might get different rates, depending on their overall financial profiles.
» Get the best rate for you: How to get the best mortgage rate
👀 If I apply now, can I get the rate I saw today?
Maybe — but even personalized rate quotes can change until you lock. That’s because lenders adjust pricing multiple times a day in response to market changes.
» Doing your research? Compare NerdWallet’s best mortgage lenders