

Mortgage rates have been high lately, and with rising home prices, it can feel like your homebuying budget gets smaller every time you check the headlines.
I track mortgage rates every week and dig into the latest housing data every month to make this article a current, grounded look at what home buyers are actually facing.
If you’re here to understand when the market will be “perfect” — pssst, it never is! The right time to buy is when the numbers and timing work for you. Whether you’re actively shopping or thinking a few moves ahead, here’s my latest pulse check on the housing market trends that matter.
Good luck out there! ✊ I’m rooting for you.
How’s the housing market right now?
The housing market rarely gives buyers everything they want at once. Looking at this month’s data, I see plenty of challenges — along with a few places where buyers may catch a break.
Here are the biggest trends I’m seeing right now:
⚠️ Mortgage rates are high (around 7%) thanks to inflation and a mix of other factors.
⚠️ Home prices just keep climbing, with year-over-year gains for 40 consecutive months.
✅ Houses spend more time on the market in the fall (about 35 days), so there’s less pressure to make a snap decision.
✅ Inventory is back up to pre-pandemic levels, meaning more homes to choose from.
What’s the best time of year to buy a house?
Lots of different forces affect the housing market. Skip ahead to read about:
Weekly average mortgage rates
Mortgage rates are down a little this week.
The interest rate on a 30-year fixed-rate mortgage averaged 6.99% annual percentage rate (APR) for the week ending Nov. 12, down two basis points from last week, according to rates provided to NerdWallet by Zillow. (A basis point is one one-hundredth of 1%.) We calculate our weekly average using daily APRs recorded over the past five business days.
Average weekly mortgage rates
Mortgage type | APR |
|---|---|
30-year fixed mortgage | 6.99% |
15-year fixed mortgage | 6.42% |
5-year adjustable | 6.82% |
Averages are for the week ending Nov. 12, 2026, according to rates provided to NerdWallet by Zillow.
To learn more about mortgage rates, check out these resources from NerdWallet:
📍 Right now: Mortgage rates today
📈 Looking ahead: Mortgage interest rates forecast
🤔 Shopping around: How to get the best mortgage rate
How do mortgage rates affect housing costs?
When mortgage rates are high, your homebuying budget doesn’t stretch as far. Let’s say you’re prepared to make a 20% down payment on a $350,000 house. Here’s what your monthly payments would look like at different interest rates:
Interest rate | Monthly principal + interest* |
|---|---|
5% | $1,503 |
5.25% | $1,546 |
5.5% | $1,590 |
5.75% | $1,634 |
6% | $1,679 |
6.25% | $1,724 |
6.5% | $1,770 |
6.75% | $1,816 |
7% | $1,863 |
7.25% | $1,910 |
7.5% | $1,958 |
7.75% | $2,006 |
*For a 30-year fixed-rate mortgage. Does not include homeowners insurance or property taxes.
Inflation and the economy
Is it a bad time to buy a house? From higher gas prices to a stagnant job market, headlines about inflation and the economy might make you feel rattled. It’s normal to feel worried about making a long-term financial commitment right now. Here’s how to stay grounded:
🤔 Consider pausing: If your finances feel shaky — for example, you’re worried about job security or paying bills — it’s wise to hold off.
😌 Stay the course: If your income is steady and your budget says the numbers work, don’t let scary “what if” headlines throw you off track.
Is it a buyer’s or seller’s market?
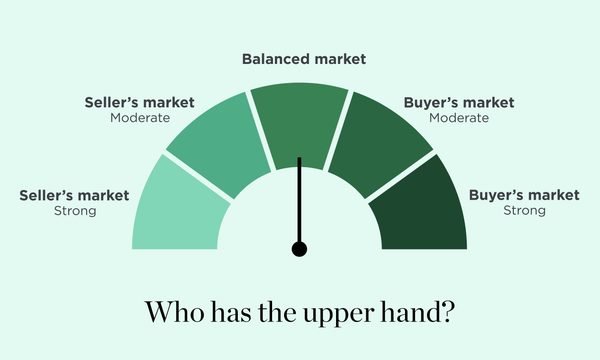
Nationally: Balanced market, but your region matters more
First, a quick definition: A buyer’s or seller’s market tells you who has more bargaining power, or room to ask for what they want, during a home sale. Affordability is a separate question. You can be in a “buyer-friendly market” and still struggle to afford a home — a reality that’s stressing out many buyers right now.
Local conditions vary. Across the U.S., there are strong seller’s markets and strong buyer’s markets, and everything in between. But a national average provides a good gut check.
Here’s what Realtor.com’s Q3 Market Clock, a report that analyzes the nation’s 100 largest housing markets, saw in July through September of this year.
Nationally, the market is balanced and heading toward a buyer-friendly direction.
Buyer’s markets are concentrated almost entirely in the South and Sun Belt.
Seller’s markets remain strongest across much of the Midwest.
What’s the difference between a buyer’s market and a seller’s market?
Whether you're in a buyer’s or seller’s market comes down to supply and demand. Available inventory affects who has the upper hand in negotiations.
📈 Buyer’s market = high inventory. Buyers have lots of choices and can take their time. Price cuts are common. Buyers might ask sellers to cover some costs or fees.
📉 Seller’s market = low inventory: Buyers have fewer choices. Prices and competition heat up. Expect multiple offers above asking price.
⚖️ Balanced market = enough homes to go around: Supply and demand are roughly even. This generally happens when a local market has about six months’ worth of available inventory.
Seasonal forces affect the housing market, too. In most places, the busiest buying season runs from April through June.
Let’s get a pulse check on sales of existing homes using September 2026 data from the National Association of Realtors (NAR).
Inventory: Growing, but demand still outpaces supply
In October, total housing inventory grew to 1.59 million units, up 1.3% from the previous month and up 4.6% from October 2025.
Unsold inventory, currently sitting at a 5.1-month supply, rose from 4.7 months in September and 4.4 months one year ago.
On one hand, rising inventory is good news — today’s home buyers have more homes to choose from. On the other hand, more options only help if you can afford them. Houses are staying on the market longer because higher mortgage rates are putting monthly payments out of reach for many buyers. October’s mortgage rates averaged above 7%, their highest since 2000 (with the exception of a single month in 2023).
“Based on the current underwhelming home sales pace at a time of consistent job growth, there could be sizable pent-up demand if mortgage rates decline,” Lawrence Yun, NAR chief economist, said in a news release.
Home prices: Still creeping higher
Meanwhile, home prices continue to inch higher, although growth has slowed compared to previous months. Nationally, year-over-year home prices have risen every month for 40 straight months — or more than three years.
The national median price for existing homes sold in September was $414,900, up 0.4% from October 2025, according to the NAR.
Year-over-year, price changes differed across three U.S. regions — Midwest, Northeast, South and West. Here’s a breakdown of median housing prices by region:
Midwest: $324,300, up 1.5%
Northeast: $519,600, up 3.2%
South: $360,900, down 0.4%
West: $624,300, unchanged
Home sales: Slowest pace in 16 years
No surprise here: When mortgage rates rise sharply, people step back from their homebuying plans. October saw a slowdown in home sales as mortgage rates above 7% put buying further out of reach. Sales of previously occupied homes fell 5.5% from September. Compared to October 2025, last month’s sales decreased 8.8%.
The slump marked the slowest sales pace since August 2010.
First-time home buyers have been hit the hardest by rising costs. They accounted for just 29% of sales in October, down from 31% last month and 32% last year. Usually, first-time home buyers make up around 40% of home sales, according to the Associated Press.
Competition: It's mild out there
The October 2026 Realtors Confidence Index, a survey of the NAR’s members, highlights recent trends real estate agents are seeing in their local markets that are easing the competition among buyers. Some trends to note:
When making an offer, it's usually between you and one other buyer. A home listed for sale received an average two offers in October, down from 2.2 offers last month and 2.1 offers last year. For context: In the era of hot bidding wars in 2021 and 2022, the average was around five offers per home.
About 1 in 10 homes are selling above list price. In October, 11% of homes sold above list price, down from 16% last month and 19% last year.
Homes are staying on the market for five weeks. Houses stayed on the market for a median 35 days in October, up from 33 days last month and 34 days last year.
» MORE: How to buy a house, step by step
DATA: What's the Homebuying Climate this month?
NerdWallet's Homebuying Climate Index puts a familiar weather label on how favorable conditions are for home buyers.
For October, our analysis puts the Climate Index at 52.5 out of 100, keeping the index in Partly Cloudy territory for the 51st straight month.
Read more about the factors affecting this month's index to gauge how they might affect your homebuying plans.
Should I buy a house now or wait?
Ultimately, whether it’s a good time to buy comes down to your personal financial readiness. If your credit score needs work or you’re in major debt, consider tackling those goals first. You also need to be emotionally ready for the commitment of owning a house.
Here are some green flags that it’s a good time to buy.
✅ Stability: You have steady income and employment, and you’re ready to stay in one place for several years.
✅ Lifestyle fit: For first-time buyers, you’re up for the responsibility of paying for maintenance and repairs. For repeat buyers, your current home no longer meets your needs: You’re ready for more space, a new neighborhood or to downsize.
✅ Savings: You'll need money for a down payment and closing costs, as well as for moving costs and other expenses.
✅ Low debt: Your debt-to-income ratio (DTI) shows how much of your monthly income goes toward paying debt (like student loans, car payments or credit cards). The lower your DTI, the better your mortgage rates and terms. A DTI of 36% or below is most attractive to lenders.
✅ Good credit score: Borrowers with credit scores of 740 and above get the best mortgage rates and terms. It’s possible to qualify with a score in the 600s, but your options are limited.
NERDY EXPERT
Chase Baysdell | Executive Loan Officer at Next Door Lending, a wholly owned subsidiary of NerdWallet
On why buyers should offer the asking price, and then ask for concessions:
“ Technically, the purchase price is irrelevant the day after you sign. It holds no value anymore. Now it's whatever somebody else wants to buy it for or what it appraises for, which is not necessarily going to be a purchase price down the road. ”
The takeaway: If you’re ready to buy, jump in now
Don’t try to time the market perfectly. National trends can be unpredictable, but if you’re in a good spot, that’s what matters most. Do you have a stable income, solid savings and a desire to settle down? You can find a way to make it work.
» MORE: Home loans for bad credit